Myth vs. Reality: Does the Fed Control Mortgage Rates in Sarasota and Lakewood Ranch?
Darren Dowling
Darren Dowling
If you're planning to buy or sell a home in Sarasota, Lakewood Ranch, Manatee County, or Charlotte County, you've probably seen plenty of headlines about the Federal Reserve and interest rates.
When the Fed changes its policy rate, many people immediately assume mortgage rates will move by the same amount.
That's a common misconception.
MYTH: The Federal Reserve sets the mortgage rates consumers pay for a home loan.
REALITY: The Federal Reserve influences financial markets and borrowing conditions, but it does not directly set the interest rate on a 30-year fixed mortgage.
Mortgage rates are influenced by several factors, including inflation, economic growth, employment conditions, investor expectations, and the bond market.
The Federal Reserve's decisions are an important part of that picture but they are not the entire picture.
This distinction matters for Florida home buyers because waiting for the Fed to make a particular move does not guarantee that mortgage rates will immediately fall.
One of the biggest influences on longer-term mortgage rates is the bond market, particularly the 10-year U.S. Treasury yield.
Investors constantly evaluate where inflation and the economy may be headed. Their expectations influence Treasury yields, and mortgage rates generally move in relation to those broader bond-market conditions.
The Federal Funds Rate is different.
The Fed uses the Federal Funds Rate as a key monetary-policy tool. When policymakers raise it, borrowing conditions throughout the economy can become tighter. When they lower it, financial conditions can become more accommodative.
But mortgage rates don't simply move one-for-one with the Fed's rate decisions.
That is why you can sometimes see the Federal Reserve raise or lower rates without seeing mortgage rates move in the same direction or by the same amount.
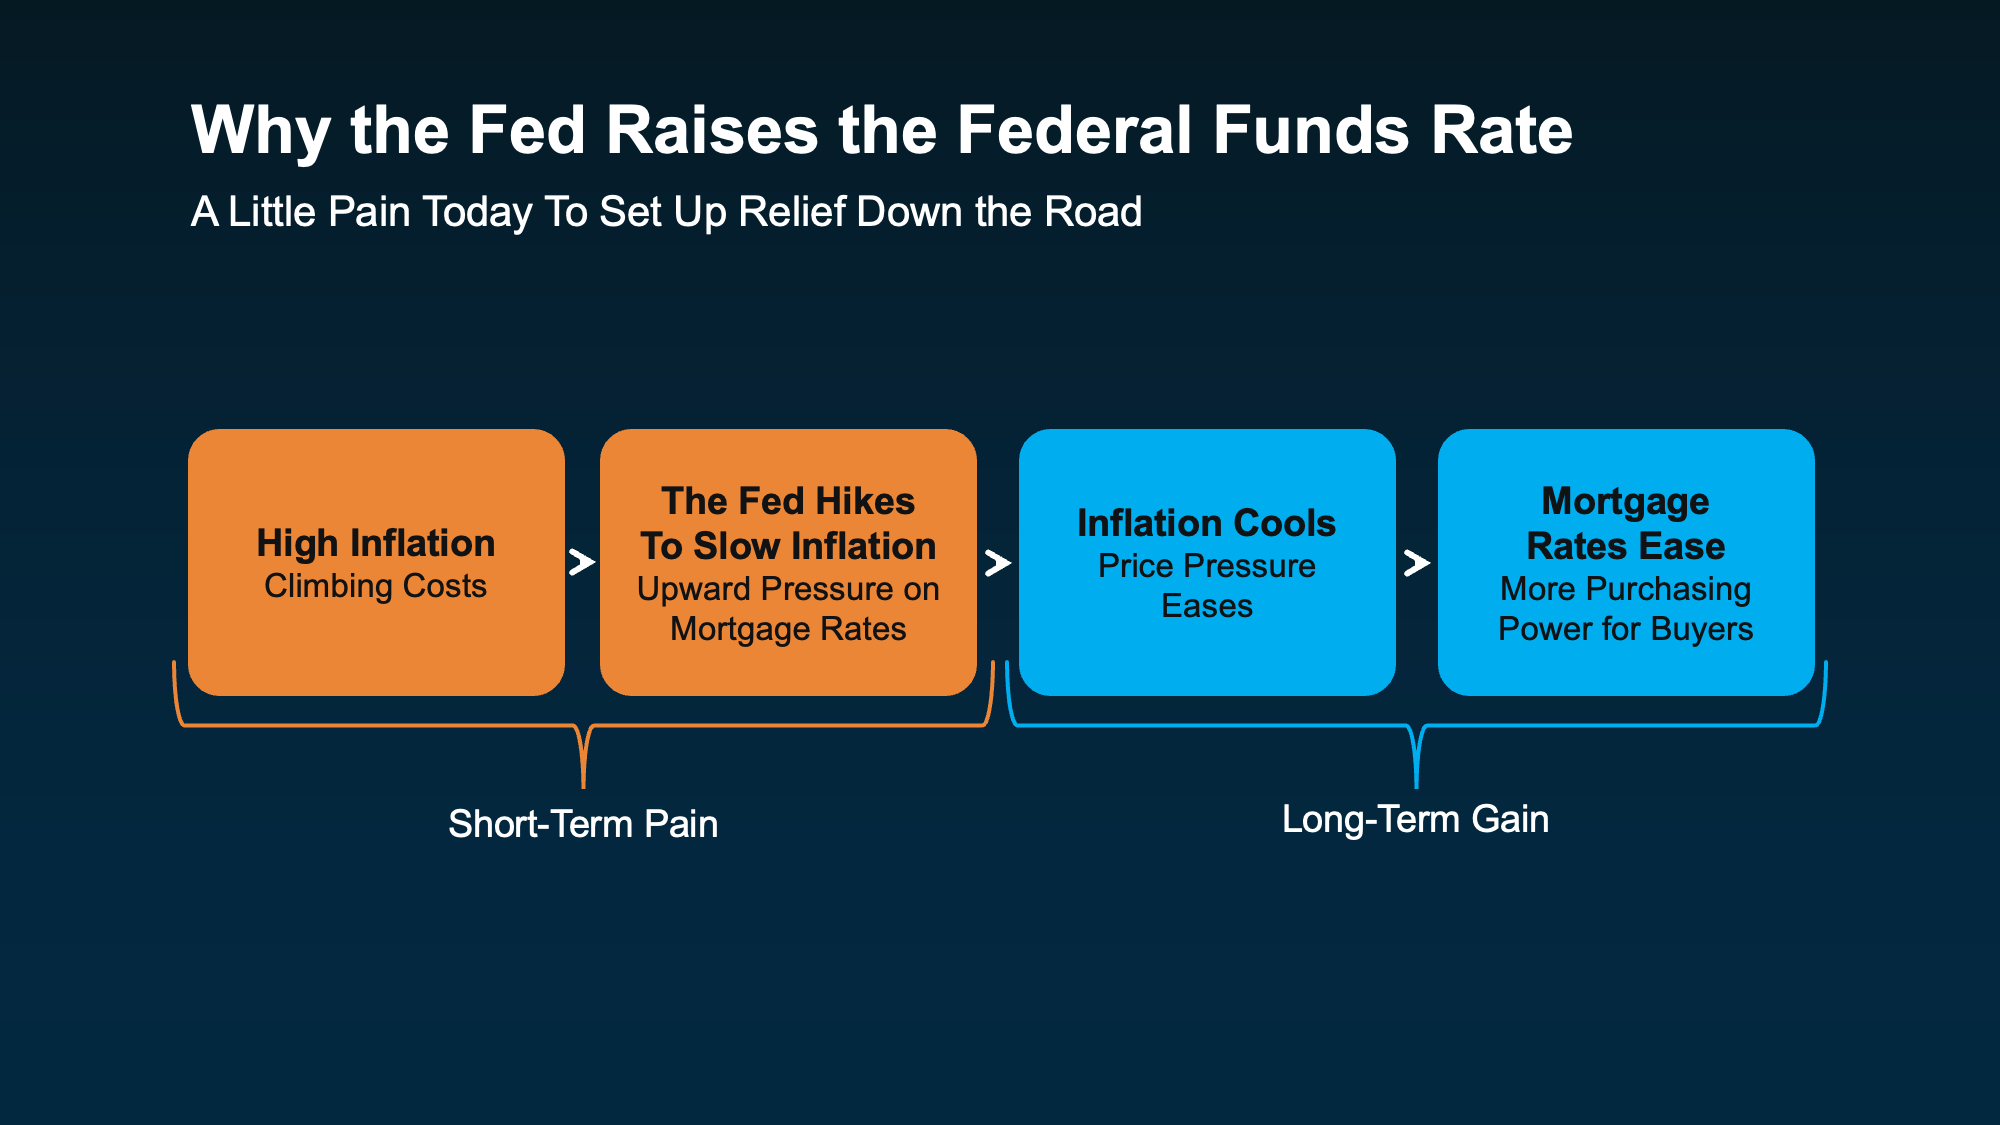
Inflation is one of the biggest factors to watch.
When inflation remains elevated, investors may expect interest rates to remain higher for longer. That can put pressure on mortgage rates and, in turn, affect how much house a buyer can comfortably afford.
This is particularly important in markets such as Sarasota and Lakewood Ranch, where buyers may be comparing resale homes with new construction, waterfront properties, golf-course communities, and master-planned communities.
A relatively small change in the mortgage rate can affect a buyer's monthly payment and purchasing power.
For example, two homes with the same purchase price can have significantly different monthly payments depending on the buyer's interest rate, down payment, taxes, insurance, and other financing costs.
That's why the right question isn't always:
"When will mortgage rates come down?"
A better question is:
"Does the home and financing plan make sense for me at today's rate?"
The Sarasota real estate market isn't controlled by the Federal Reserve alone.
Local inventory, pricing, insurance costs, new construction, seasonal demand, employment, migration, and buyer preferences all influence the market.
Recent Sarasota County data illustrates why local market conditions matter. July 2026 single-family data showed a $493,500 median sale price, while active inventory was down substantially from the previous year.
That means buyers aren't simply navigating "the Florida housing market." They're navigating a specific local market and often an even more specific neighborhood or property type.
A buyer considering:
may encounter very different inventory, pricing, and competition.
Lakewood Ranch deserves particular attention because of its unique combination of new construction, master-planned communities, lifestyle amenities, and continued residential growth.
Current market data shows that Lakewood Ranch remains an active market, with Redfin reporting a median sale price around $624,000 for the three months ending August 2026 and homes selling faster than the previous year.
For buyers considering Lakewood Ranch, mortgage rates are only one part of the decision.
You also need to compare:
A builder offering a mortgage-rate incentive, for example, can sometimes create a different financial picture than a similarly priced resale home.
That's why comparing the total cost of ownership, rather than simply comparing list prices, is so important.
The same principle applies throughout the broader Sarasota–Manatee–Charlotte region.
Manatee County, which includes much of Lakewood Ranch, has its own market dynamics. July 2026 single-family data showed a $495,000 median sale price and 4.1 months of supply, demonstrating why county-level conditions can differ from Sarasota County.
Charlotte County also has a distinct market profile. Recent 2026 data showed a $353,545 median single-family sale price in July, with closed sales up year over year. Beyond Realty
For buyers relocating to Southwest Florida, this creates opportunities to compare markets rather than focusing exclusively on mortgage rates.
Someone deciding between Sarasota, Lakewood Ranch, Bradenton, Venice, North Port, Port Charlotte, or Punta Gorda may find that the same monthly housing budget produces very different options depending on location.
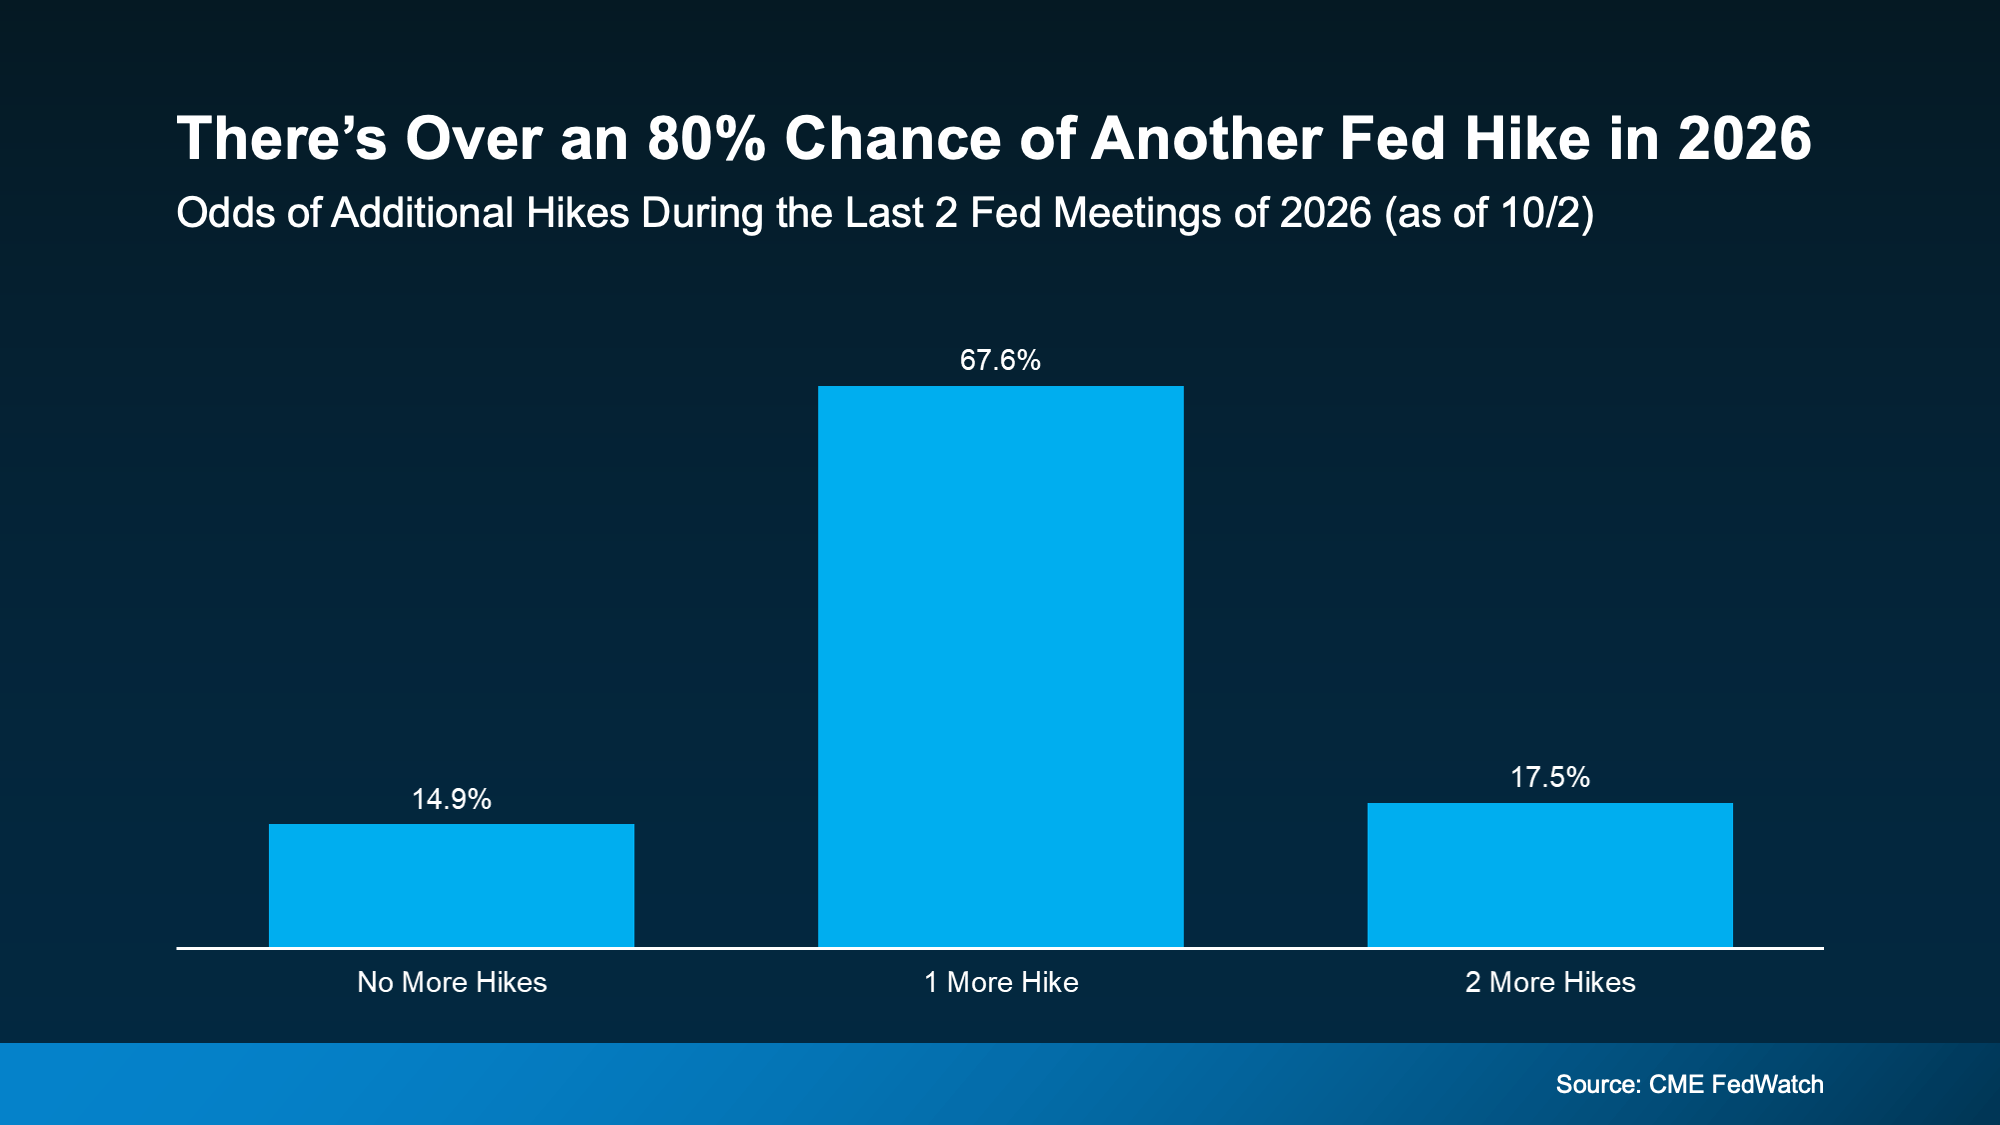
Federal Reserve policy can change as economic conditions change.
If inflation remains persistent, policymakers may maintain tighter monetary policy for longer. If inflation continues to cool and economic conditions weaken, financial markets may begin anticipating lower rates.
But predicting exactly when mortgage rates will fall and how far they will fall is difficult.
That's why making a real estate decision based entirely on a forecast can be risky.
Instead, buyers should focus on the factors they can actually control.
1. Get Pre-Approved Before You Shop
A strong pre-approval gives you a realistic understanding of your purchasing power.
It also allows you to compare homes based on an actual financing scenario rather than relying on an online mortgage calculator.
2. Compare the Entire Monthly Payment
Don't look only at the purchase price or mortgage rate.
Consider:
This is particularly important in Southwest Florida, where insurance and community costs can vary significantly from one property to another.
3. Look at Rate-Buydown Opportunities
For some buyers, a seller concession or builder incentive may be more valuable than a reduction in the purchase price.
This is especially worth investigating when comparing new construction in Lakewood Ranch with resale properties.
Your lender can help determine which option produces the better financial result for your specific situation.
4. Don't Automatically Wait for Lower Rates
Waiting can make sense in some circumstances but it can also have a cost.
If mortgage rates eventually decline, more buyers may re-enter the market. Increased competition could affect pricing and negotiation leverage.
There is no guarantee that waiting for a lower rate will result in a lower overall cost.
5. Remember That Refinancing May Be an Option
A home purchase doesn't necessarily lock you into today's mortgage rate forever.
If rates fall meaningfully in the future and the numbers make sense, refinancing may become an option.
That doesn't mean buyers should purchase a home they cannot comfortably afford today. It simply means today's financing environment doesn't necessarily determine the entire lifetime of a mortgage.
Mortgage rates don't only affect buyers.
They can also influence the number of potential buyers who can comfortably afford a home.
For sellers in Sarasota, Lakewood Ranch, Bradenton, Venice, North Port, and surrounding communities, pricing strategy becomes especially important when buyers are sensitive to monthly payments.
Overpricing a property can cause it to sit on the market while competing homes attract buyers.
A seller may also want to consider whether a closing-cost credit, rate buydown, or other concession could make the property more attractive than simply reducing the asking price.
The best strategy depends on the property, neighborhood, competition, condition, and current buyer demand.
The Federal Reserve does not directly control mortgage rates.
Fed policy can influence the broader financial environment, but mortgage rates also respond to inflation, Treasury yields, economic expectations, investor demand, and other market forces.
For home buyers and sellers in Sarasota County, Manatee County, Lakewood Ranch, and Charlotte County, that means there isn't a single Fed announcement that determines whether it is the "right" time to move.
The better approach is to understand your local market, evaluate your financing options, and make a decision based on your personal goals and financial comfort.
Whether you're considering a Sarasota home, Lakewood Ranch new construction, a Manatee County property, or a home in Charlotte County, a local real estate strategy can help you evaluate the opportunity beyond the headlines.
If you're considering buying or selling in Sarasota or Lakewood Ranch, Darren Dowling can help you evaluate the market, compare your options, and build a strategy around your specific goals.
Contact Darren Dowling at Beyond Realty for a strategic, no-pressure conversation about your next move in Sarasota, Lakewood Ranch, Manatee County, or Charlotte County.
Beyond Realty
2170 Main Street, Suite 103, Sarasota, FL 34237
941-204-0493
Darren Dowling is a Sarasota-based Realtor® and the founder of Beyond Realty, specializing in Sarasota and Lakewood Ranch residential real estate, new construction, and relocation.
How VA Home Loan Benefits, More Negotiating Opportunities, and Local Real Estate Market Conditions Could Help Veterans and Active-Duty Service Members Buy a Home in Sa… Read more
What Buyers and Sellers Need to Know About Mortgage Rates, Home Values, and Real Estate Market Trends in Sarasota, Lakewood Ranch, Manatee County, and Charlotte County.
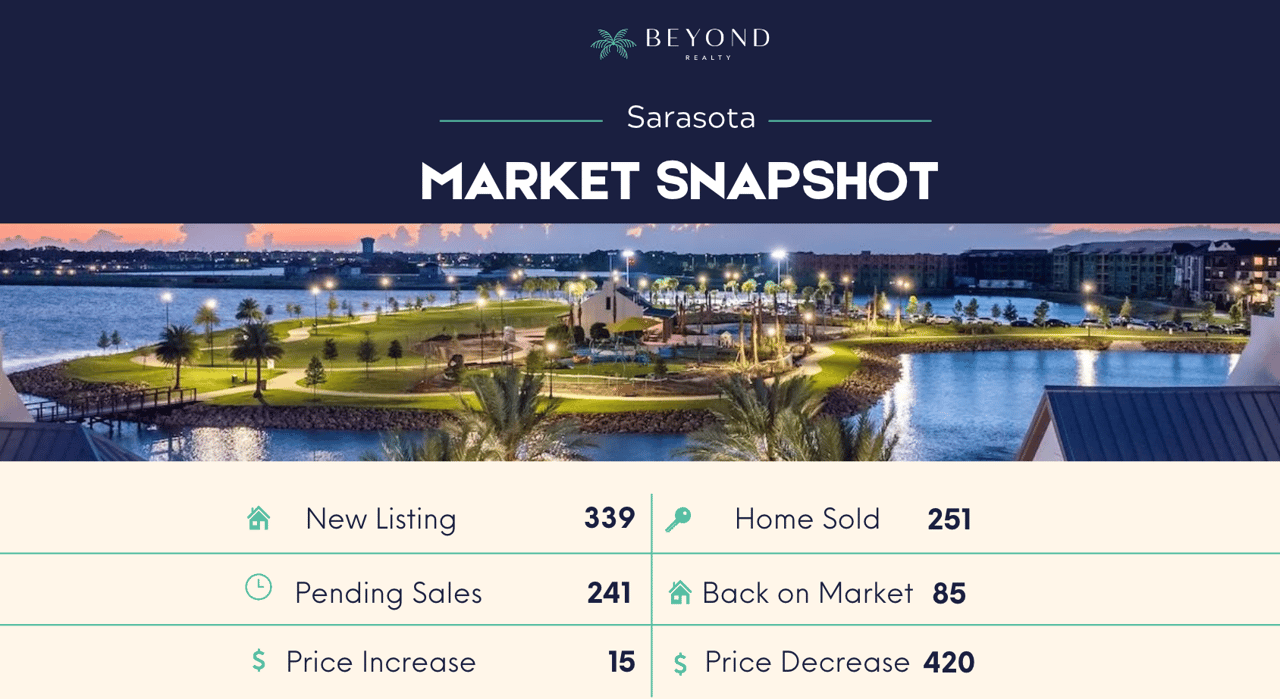
Closed Sales and Pending Activity Rise in Sarasota County as Pricing Adjustments Continue Across Both Markets
You’ve got questions and we can’t wait to answer them.