Leave a Message

Thank you for your message. We will be in touch with you shortly.

The Down Payment Assistance You Didn’t Know About

Beyond Realty

The Down Payment Assistance You Didn’t Know About

The Down Payment Assistance You Didn’t Know About


Believe it or not, almost 80% of first-time homebuyers qualify for down payment assistance, but only 13% actually use it. And if you’re hoping to buy a home, this is a mission-critical gap to close – fast (see graph below):
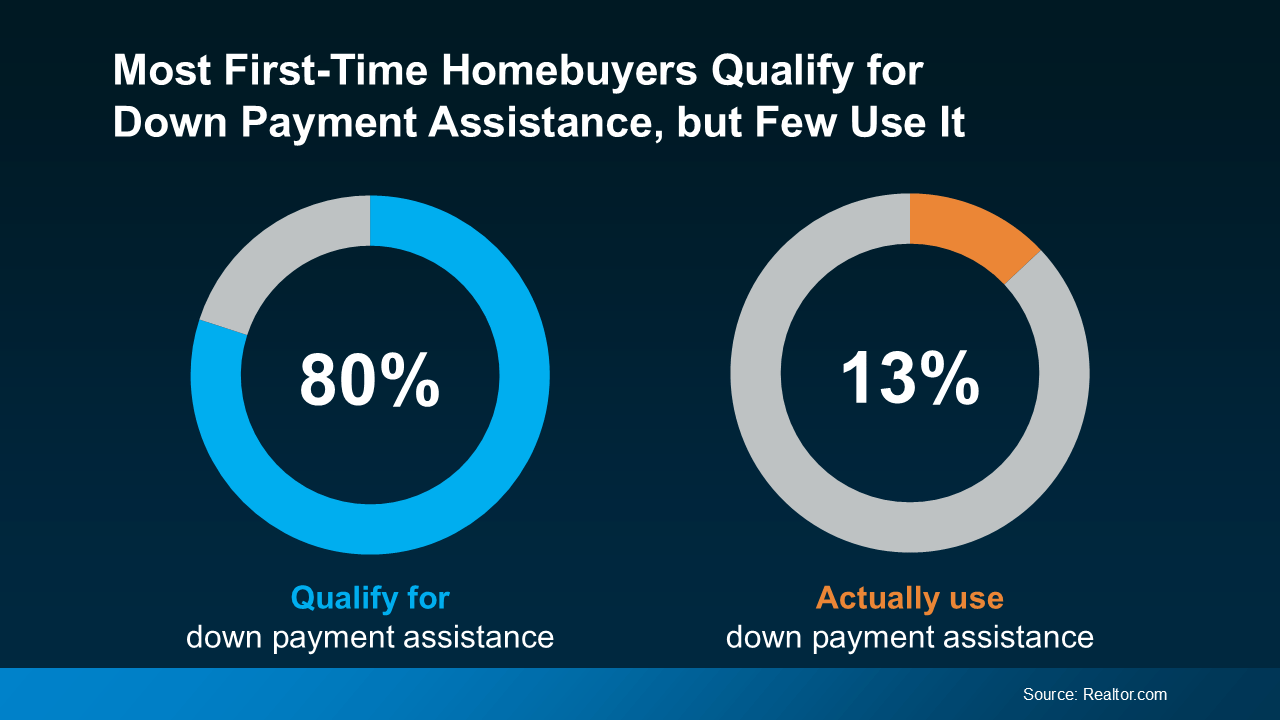
No Caption ReceivedHere’s what you need to know to make the most of your down payment in today’s housing market.

Amplify Your Down Payment Potential

For first-time buyers, the name of the game with down payments is making sure you’re taking advantage of all the resources out there designed to help you. And a bunch of them can get you to your goal faster than you may have thought possible.

For example, there are loan options that require as little as 3% down, or even 0% for certain qualified borrowers, like Veterans. And let’s not forget down payment assistance, like grants and other opportunities, that help you cover the upfront cost of your down payment.

If you’re interested in exploring those options and what you may be able to use to your advantage, connect with a trusted lender. Because if you don't at least see what’s available, you could be leaving money on the table and missing your chance at buying a home. These resources can boost your down payment. And a higher down payment could help lower your eventual monthly mortgage payment, and even avoid or reduce your fees like private mortgage insurance.

Don’t Let News Headlines About Down Payments Scare You

There’s one more thing to address. News coverage has been talking about how the typical down payment is rising. A report from Redfin states:

“The typical down payment for U.S. homebuyers hit a record high of $67,500 in June, up 14.8% from $58,788 a year earlier . . . This was the 12th consecutive month the median down payment rose year over year.”

But don’t let those high dollars scare you. Just because the average down payment is rising doesn’t mean down payment requirements are going up. That’s a key piece of the puzzle to understand. It’s really just because people are choosing to put more down to try to offset higher mortgage rates, and current homeowners who are putting their equity to work are using that to increase their down payment on their next home. As HousingWire explains:

“. . . buyers are putting down a higher percentage of the purchase price to lower their monthly mortgage payment. And buyers also had more equity from their home sales, which gives them more cushion.”

Let’s break those two reasons down a bit:

1. A bigger down payment helps lower your monthly mortgage payment. Affordability has been a challenge for many buyers recently, which is why those who have the ability to make a bigger down payment are going to do so in an effort to lower their future housing costs.

2. Buyers who already own a home have a record amount of equity to leverage. Someone who bought a home a few years ago has gained a significant amount of value in their house, thanks to home price appreciation. These people can put down much more than the average first-time buyer who hasn’t owned a home yet.

Bottom Line

What’s the best thing to do? Talk with a trusted lender about your options. They’ll help you figure out where you stand today and how to access the resources you may qualify for. Because help is out there, you just need to work with a pro to take advantage of it.
Recent Blog Posts

Mastering the Market: Your Guide to Pricing and Selling Your Home in Sarasota, Manatee, and Charlotte Counties

A practical guide to pricing your home competitively, attracting qualified buyers, and navigating the Sarasota-area real estate market. Copy
Why Most People Are Still Glad They Bought a Home With everything going on, it’s understandable if you’re wondering if you’d regret buying right now.  Everyday expenses cost more. Mortgage rates are higher than you’d like. And when the economy feels uncertain, taking on a mortgage can feel like a much bigger leap. But here’s some perspective that may help… Most people who already made that leap would do it again. According to a recent survey from NerdWallet, the vast majority of recent buyers (74%) were glad they bought their current home. Only a very small 3% of people regret it: And here’s a big reason why so many people feel it was worth it, even now. Homeownership Is a Long-Term PlayWhen you’re deciding whether to buy, it’s easy to focus on what’s happening right now. What’s today’s mortgage rate? Are prices going up or down? Those things matter. But don’t get so caught up in buying in the perfect moment that you miss the bigger picture. A home isn’t typically something you buy for just a year or two. It’s a longer-term play. And when you zoom out, it all starts to fall into perspective – especially if you look at home prices and equity. According to data from the Federal Housing Finance Agency (FHFA), home prices nationally have risen 33.4% over just the past five years (see map below): And that appreciation has helped current homeowners build some serious wealth. Research from Bankrate shows homeowners gained an average of nearly $150,000 in wealth over the past five years as equity steadily rose across 90% of major metro areas. That’s one of the biggest benefits of homeownership. As you pay down your mortgage and your home appreciates over time, your ownership stake – your equity – can grow. Now, Zoom Out Even FurtherThe five-year numbers are impressive. But the numbers get even more dramatic when you look at decades instead of individual market cycles. FHFA data shows home prices nationally have risen 336% since 1991. Sit with that for a second. Three hundred percent (see map below):   That doesn't mean prices go up every single year. And it doesn't mean buying is automatically the right decision for everyone today. You should only buy when the numbers (and the payment) work for you. What it does show is why trying to perfectly time the market can make you miss the bigger picture.  Over time, homeowners gain a lot of equity. And that equity can eventually become a powerful financial resource. As Freddie Mac explains:  “Your home's equity is part of your total wealth as a homeowner. If you decide to sell your home, the equity you have built over time will come back to you in the sale. . . If it's time to upsize or downsize, you can use that cash for the down payment on your next home.” Basically, if you can afford to do it, buying a home now could set you up for future moves. And just in case you’re someone who’s worried about what happens if prices do fall, after you buy, remember: you’re not buying for one year. Prices can dip. They have before. But historically, they’ve risen far more over the long run. And the longer you own your home, the more time you have to ride out those ups and downs and keep building equity. Bottom LineDon’t let today’s uncertainty make you lose sight of what homeownership can do over time. Most homeowners say they’d make the same choice again. And decades of home-price growth help explain why. If you’re wondering whether buying makes sense for you right now, let’s look at the numbers together – and what owning a home could mean for you in the years ahead.

Discover how long-term homeownership can help build equity and financial stability, and what buyers should consider when purchasing a home in Sarasota, Lakewood Ranch,… Read more
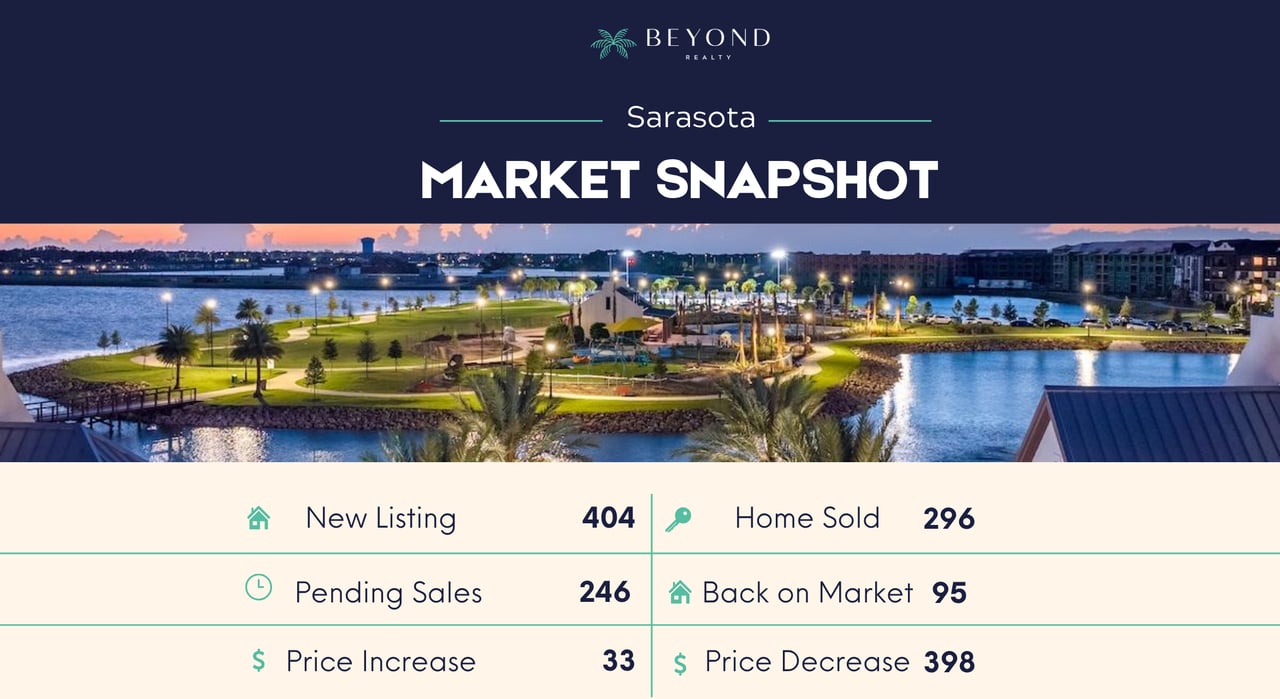
Sarasota market snapshot infographic with waterfront panorama and real estate sales statistics.
🏠 Home Sale Market Snapshot: Sarasota & Manatee Counties | October 2–8, 2026

A Fountain powerboat speeds across ocean water as a helicopter flies overhead.
Sarasota Weekend Events: October 10–11, 2026

From offshore powerboat racing and classic cars to live music, soccer, and Oktoberfest fun, discover what’s happening around Sarasota this weekend.
Aerial view of a bridge over turquoise water beside a white-sand beach and coastal homes.
Sarasota, Manatee & Charlotte County Market Report (August 2026): Two Counties Crossed Into Seller's Markets. All Three Sold Fewer Homes.

Magnifying glass enlarges a house symbol surrounded by percent signs.
Myth vs. Reality: Does the Fed Control Mortgage Rates in Sarasota and Lakewood Ranch?

What Federal Reserve decisions really mean for mortgage rates, home affordability, and real estate decisions across Sarasota, Lakewood Ranch, Manatee County, and Charl… Read more

Let's Talk

You’ve got questions and we can’t wait to answer them.
Follow Us on Instagram