The Hidden Costs of Florida Homeownership (And How to Budget for Them)
Darren Dowling
Darren Dowling
Buying a home in Florida is an exciting milestone but the purchase price is just one piece of the puzzle. To confidently plan your move or next property purchase, you need a full picture of the ongoing and upfront expenses that come with homeownership in the Sunshine State.
This guide breaks down the most common “hidden” costs, how they work, and real-world example budgets so you can prepare financially and avoid surprises.
Florida has some of the highest homeowners insurance premiums in the U.S. due to hurricane risk and a challenging insurance market, with typical annual premiums ranging from $3,000 to $7,000 (or more) depending on location and property features.
Homeowners insurance protects your dwelling and personal property against fire, theft, and many weather-related damages.
In many parts of Florida, especially coastal and low-lying areas, flood insurance is required by lenders and strongly recommended even outside high-risk zones. Premiums can vary widely from around $1,000 to $10,000+ annually depending on elevation and flood zone.
Windstorm coverage is often bundled or required in coastal areas, and umbrella policies offer extra liability protection beyond your base insurance. Costs vary widely based on coverage amount and property details.
Budget Tip: Request multiple quotes and ask for wind mitigation or strengthened roof discounts both can reduce premiums.
Florida’s property tax rates are moderate compared to some other states, averaging roughly 0.8%–1.0% of assessed value annually. On a $500,000 home, that equates to about $4,000–$5,000/year.
Homeowners who occupy their home as a primary residence can apply for the state’s Homestead Exemption, which can reduce taxable value by up to $50,000 and cap annual assessed increases.
Keep in mind:
Property taxes are due annually and often escrowed through your mortgage.
They increase as your home appreciates or local millage rates change.
Many Florida neighborhoods especially condos and master-planned communities have Homeowners Association (HOA) fees.
Common inclusions:
Landscaping
Exterior maintenance
Community amenities (pools, clubhouses, security)
Some utilities or trash services
Typical HOA monthly fees span from $200–$1,000+, depending on the community and amenities.
HOAs may also levy special assessments for major repairs or upgrades like roof replacements or compliance with codes. Budget an additional 10–15% annually to cushion for these.
Florida’s subtropical climate means air conditioning runs frequently and electric bills can be higher than many buyers expect.
Typical monthly utility ranges include:
Electricity: $150–$300+
Water & Sewer: $40–$150
Internet/Cable: $60–$200
Garbage and recycling may be additional if not included in HOA or municipal services.
Routine maintenance is inevitable and essential to preserve your home’s value.
Common year-round and seasonal services:
HVAC servicing: ~$150–$400/year
Pool care: ~$80–$150/month
Pest control: ~$30–$100/month
Lawn care & landscaping: $100–$300/month
Roof inspection/repairs, exterior upkeep: varies widely
A general rule of thumb for maintenance and repairs is 1–2% of the home’s value annually.
Closing costs are fees paid at the time of closing and usually total 2%–5% of your home’s purchase price. These include:
Loan origination fees
Appraisal and inspection fees
Title search & insurance
Recording fees and prepaid taxes/insurance
On a $500,000 home, that’s $10,000–$25,000+ beyond your down payment.
Here’s how those costs can stack up across different price points. These examples assume typical insurance, taxes, HOA, utilities, and maintenance but will vary by location and property details:
Property taxes (~1%): $5,000
Homeowners insurance: $5,000
Flood insurance: $1,500
HOA fees ($300/mo): $3,600
Utilities: $3,000
Maintenance reserve (1.5%): $7,500
Total: ~ $25,600/year
Plus mortgage payment
Property taxes: $7,000
Homeowners insurance: $7,000
Flood insurance: $2,000
HOA ($400/mo): $4,800
Utilities: $3,500
Maintenance reserve (1.5%): $10,500
Total: ~ $41,800/year
Property taxes: $10,000
Homeowners insurance: $10,000
Flood insurance: $3,000
HOA ($600/mo): $7,200
Utilities: $4,000
Maintenance reserve (1.5%): $15,000
Total: ~ $49,200/year
Owning a home in Florida offers incredible lifestyle benefits from no state income tax to year-round sunshine but the true cost of ownership only becomes clear when all expenses are considered.
Planning ahead for insurance, property taxes, HOA dues, utilities, and ongoing maintenance isn’t optional it’s essential for avoiding surprises and protecting your long-term financial comfort.
With the right preparation and local insight, you can enjoy everything Florida homeownership has to offer with clarity and confidence.
Beyond Realty
2170 Main Street, Suite 103, Sarasota, FL 34237
941-204-0493
Darren Dowling is a Sarasota-based Realtor® and the founder of Beyond Realty, specializing in Sarasota and Lakewood Ranch residential real estate, new construction, and relocation.
Rising mortgage rates, growing housing inventory, and longer selling times are creating new opportunities in Sarasota, Lakewood Ranch, Manatee County, and Charlotte Co… Read more
A practical guide to pricing your home competitively, attracting qualified buyers, and navigating the Sarasota-area real estate market. Copy
Discover how long-term homeownership can help build equity and financial stability, and what buyers should consider when purchasing a home in Sarasota, Lakewood Ranch,… Read more
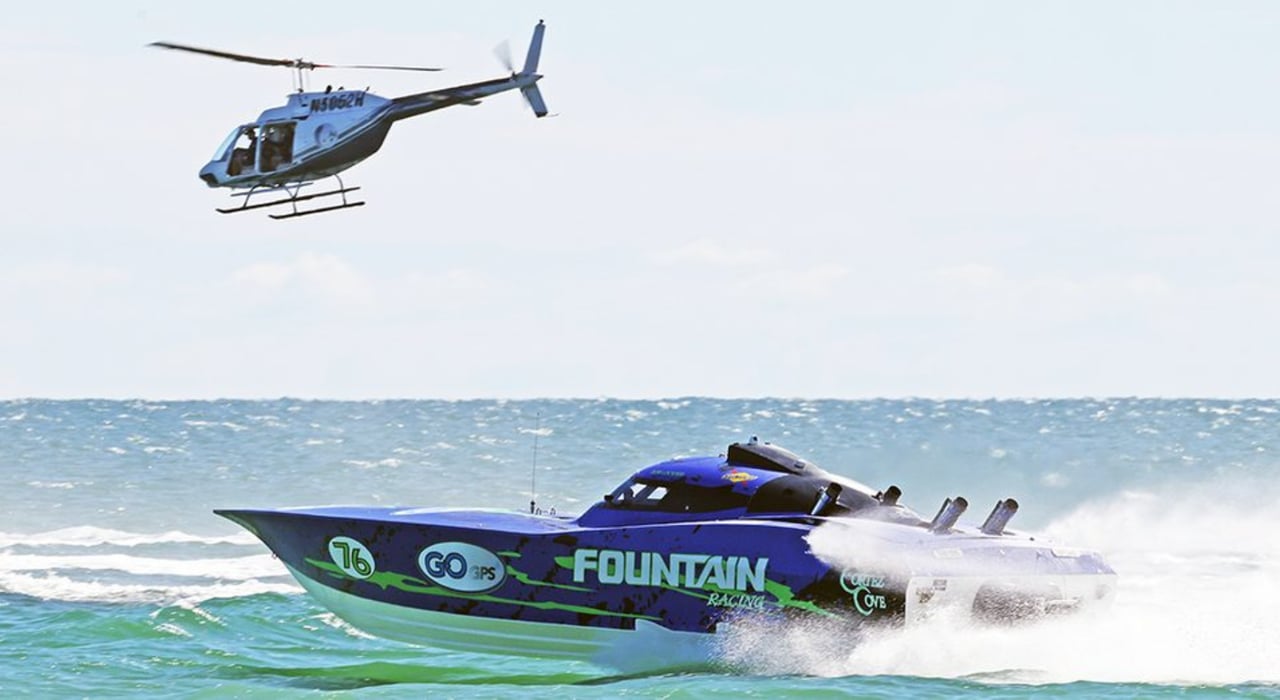
From offshore powerboat racing and classic cars to live music, soccer, and Oktoberfest fun, discover what’s happening around Sarasota this weekend.
You’ve got questions and we can’t wait to answer them.