Leave a Message

Thank you for your message. We will be in touch with you shortly.

The Main Key To Understanding the Rise in Mortgage Rates

Beyond Realty

Real Estate
The Main Key To Understanding the Rise in Mortgage Rates
The Main Key To Understanding the Rise in Mortgage Rates | MyKCM

Every Thursday, Freddie Mac releases the results of their Primary Mortgage Market Survey which reveals the most recent movement in the 30-year fixed mortgage rate. Last week, the rate was announced as 3.01%. It was the first time in three months that the mortgage rate surpassed 3%. In a press release accompanying the survey, Sam Khater, Chief Economist at Freddie Mac, explains:

“Mortgage rates rose across all loan types this week as the 10-year U.S. Treasury yield reached its highest point since June.”

The Main Key To Understanding the Rise in Mortgage Rates | MyKCM

The reason Khater mentions the 10-year U.S. Treasury yield is because there has been a very strong relationship between the yield and the 30-year mortgage rate over the last five decades. Here’s a graph showing that relationship:The relationship has also been consistent throughout 2021 as evidenced by this graph:The graph also reveals the most recent jump in mortgage rates was preceded by a jump in the 10-year Treasury rate (called out by the red circles).

So, What Impacts the Yield Rate?

According to Investopedia:

“There are a number of economic factors that impact Treasury yields, such as interest rates, inflation, and economic growth.”

Since there are currently concerns about inflation and economic growth due to the pandemic, the Treasury yield spiked last week. That spike impacted mortgage rates.

What Does This Mean for You?

Khater, in the Freddie Mac release mentioned above, says:

“We expect mortgage rates to continue to rise modestly which will likely have an impact on home prices, causing them to moderate slightly after increasing over the last year.”

Nadia Evangelou, Senior Economist and Director of Forecasting for the National Association of Realtors (NAR), also addresses the issue:

“Consumers shouldn’t panic. Keep in mind that even though rates will increase in the following months, these rates will still be historically low. The National Association of REALTORS forecasts the 30-year fixed mortgage rate to reach 3.5% by mid-2022.”

Bottom Line

Forecasting mortgage rates is very difficult. As Mark Fleming, Chief Economist at First American, once quipped:

“You know, the fallacy of economic forecasting is don’t ever try and forecast interest rates and or, more specifically, if you’re a real estate economist mortgage rates, because you will always invariably be wrong.”

That being said, if you’re either a first-time homebuyer or a current homeowner thinking of moving into a home that better fits your current needs, keep abreast of what’s happening with mortgage rates. It may very well impact your decision.
Recent Blog Posts

Mastering the Market: Your Guide to Pricing and Selling Your Home in Sarasota, Manatee, and Charlotte Counties

A practical guide to pricing your home competitively, attracting qualified buyers, and navigating the Sarasota-area real estate market. Copy
Why Most People Are Still Glad They Bought a Home With everything going on, it’s understandable if you’re wondering if you’d regret buying right now.  Everyday expenses cost more. Mortgage rates are higher than you’d like. And when the economy feels uncertain, taking on a mortgage can feel like a much bigger leap. But here’s some perspective that may help… Most people who already made that leap would do it again. According to a recent survey from NerdWallet, the vast majority of recent buyers (74%) were glad they bought their current home. Only a very small 3% of people regret it: And here’s a big reason why so many people feel it was worth it, even now. Homeownership Is a Long-Term PlayWhen you’re deciding whether to buy, it’s easy to focus on what’s happening right now. What’s today’s mortgage rate? Are prices going up or down? Those things matter. But don’t get so caught up in buying in the perfect moment that you miss the bigger picture. A home isn’t typically something you buy for just a year or two. It’s a longer-term play. And when you zoom out, it all starts to fall into perspective – especially if you look at home prices and equity. According to data from the Federal Housing Finance Agency (FHFA), home prices nationally have risen 33.4% over just the past five years (see map below): And that appreciation has helped current homeowners build some serious wealth. Research from Bankrate shows homeowners gained an average of nearly $150,000 in wealth over the past five years as equity steadily rose across 90% of major metro areas. That’s one of the biggest benefits of homeownership. As you pay down your mortgage and your home appreciates over time, your ownership stake – your equity – can grow. Now, Zoom Out Even FurtherThe five-year numbers are impressive. But the numbers get even more dramatic when you look at decades instead of individual market cycles. FHFA data shows home prices nationally have risen 336% since 1991. Sit with that for a second. Three hundred percent (see map below):   That doesn't mean prices go up every single year. And it doesn't mean buying is automatically the right decision for everyone today. You should only buy when the numbers (and the payment) work for you. What it does show is why trying to perfectly time the market can make you miss the bigger picture.  Over time, homeowners gain a lot of equity. And that equity can eventually become a powerful financial resource. As Freddie Mac explains:  “Your home's equity is part of your total wealth as a homeowner. If you decide to sell your home, the equity you have built over time will come back to you in the sale. . . If it's time to upsize or downsize, you can use that cash for the down payment on your next home.” Basically, if you can afford to do it, buying a home now could set you up for future moves. And just in case you’re someone who’s worried about what happens if prices do fall, after you buy, remember: you’re not buying for one year. Prices can dip. They have before. But historically, they’ve risen far more over the long run. And the longer you own your home, the more time you have to ride out those ups and downs and keep building equity. Bottom LineDon’t let today’s uncertainty make you lose sight of what homeownership can do over time. Most homeowners say they’d make the same choice again. And decades of home-price growth help explain why. If you’re wondering whether buying makes sense for you right now, let’s look at the numbers together – and what owning a home could mean for you in the years ahead.

Discover how long-term homeownership can help build equity and financial stability, and what buyers should consider when purchasing a home in Sarasota, Lakewood Ranch,… Read more
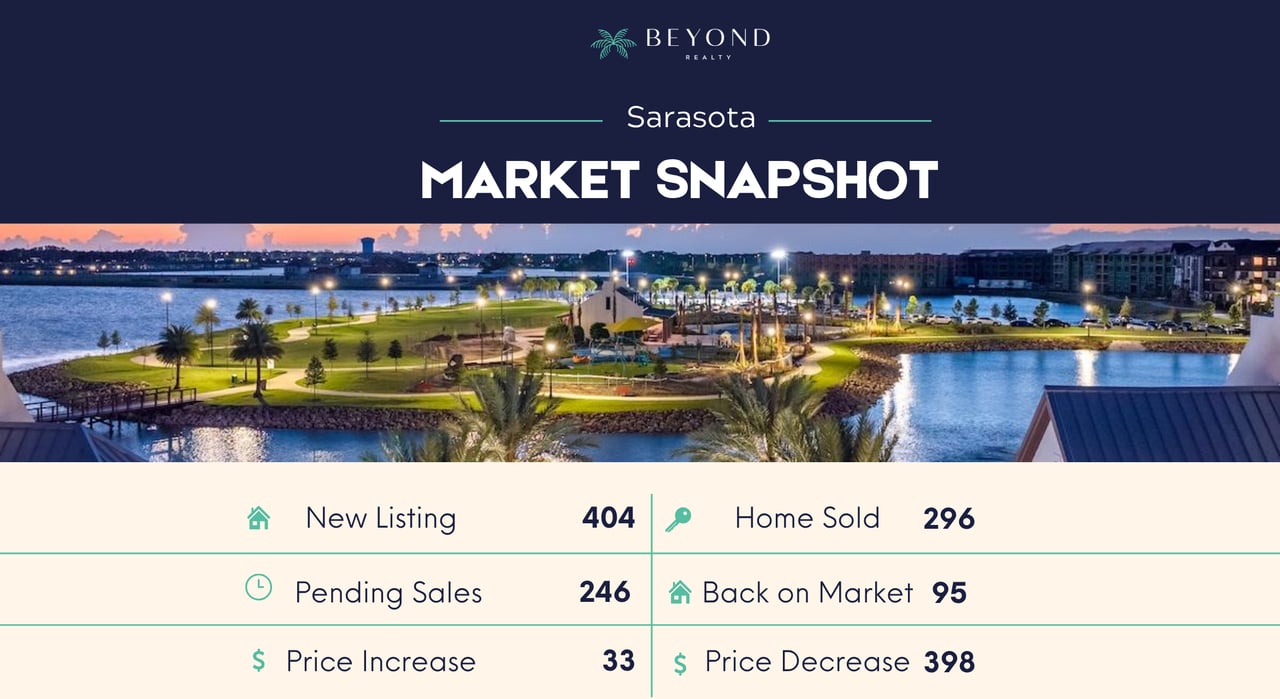
Sarasota market snapshot infographic with waterfront panorama and real estate sales statistics.
🏠 Home Sale Market Snapshot: Sarasota & Manatee Counties | October 2–8, 2026

A Fountain powerboat speeds across ocean water as a helicopter flies overhead.
Sarasota Weekend Events: October 10–11, 2026

From offshore powerboat racing and classic cars to live music, soccer, and Oktoberfest fun, discover what’s happening around Sarasota this weekend.
Aerial view of a bridge over turquoise water beside a white-sand beach and coastal homes.
Sarasota, Manatee & Charlotte County Market Report (August 2026): Two Counties Crossed Into Seller's Markets. All Three Sold Fewer Homes.

Magnifying glass enlarges a house symbol surrounded by percent signs.
Myth vs. Reality: Does the Fed Control Mortgage Rates in Sarasota and Lakewood Ranch?

What Federal Reserve decisions really mean for mortgage rates, home affordability, and real estate decisions across Sarasota, Lakewood Ranch, Manatee County, and Charl… Read more

Let's Talk

You’ve got questions and we can’t wait to answer them.

Follow Us on Instagram