Wellen Park’s New Construction: Why Buyers Love This Growing Community
Darren Dowling

Darren Dowling
Buying new construction in Wellen Park, ZIP 34293 in the City of North Port, means signing a builder contract instead of the standard FAR/BAR AS IS contract. You keep fewer default protections, so your leverage comes from the deposit schedule, an independent inspection, and a written insurance quote before you commit.
Key takeaways
In a resale you use the standard FAR/BAR AS IS contract, with a defined inspection period during which you can cancel and recover your deposit. In new construction you sign the builder's own agreement, and that protection is not automatic.
Item | Typical resale purchase | Typical new construction purchase |
|---|---|---|
The contract | FAR/BAR AS IS, a widely used standard form | The builder's own purchase agreement, drafted by the builder's counsel |
Inspection rights | Defined inspection period with a right to cancel | Varies by builder, and is often narrower than buyers expect |
Deposit | Escrowed, usually refundable during the inspection period | Often becomes non-refundable at defined milestones |
Price negotiation | Direct, on price | Often through incentives rather than base price |
Completion date | A specific closing date | An estimated date, subject to change |
Warranty | Generally none from the seller | Builder warranty, with defined terms and a claims process |
Who represents you | Your agent | The sales agent in the model home represents the builder |
None of this makes new construction a bad purchase. Much of it is reasonable from the builder's side. It simply means the default protections are different, and you should know which ones you have before you sign rather than after.
Yes, and register your representation on your very first visit. In almost every case the builder offers to pay the buyer’s agent fee, and once you have visited unrepresented some builders will not recognize an agent afterward.
The sales consultant in the model home is a licensed professional working for the builder. That is their job and there is nothing improper about it. But they are not the person to ask whether the district assessment on lot 47 is higher than on lot 12, whether the lot behind you is planned for a road, or whether your insurance quote is going to land where you assumed.
What independent representation actually does on a new construction purchase.
Reads the builder agreement before you sign, and flags the deposit milestones and the change order terms. Compares the lot premium to what the lot actually gets you. Pulls the district assessment for the specific parcel from the county tax roll. Orders an independent inspection at the pre-drywall stage and again before closing. Gets a live insurance quote on the planned structure. Tracks the warranty claim window after you move in.
Two at minimum, and neither of them is the county inspection. Order a pre-drywall inspection while the framing, plumbing, electrical and mechanical work are still visible, and a full final inspection before closing.
Inspection | When | What it catches |
|---|---|---|
Pre-drywall | After framing, rough plumbing, electrical and HVAC, before insulation and drywall | Framing defects, missing fasteners, plumbing and duct issues that become invisible later |
Final walkthrough inspection | Before closing | Finish defects, appliance and system function, grading and drainage, window and door operation |
Eleven month warranty inspection | Before the first year warranty period expires | Settlement cracks, system issues and defects that emerge in the first year, while still covered |
Wind mitigation inspection | At or near completion | Documents features that reduce your insurance premium |
Elevation certificate, where applicable | At completion | Required for flood insurance rating in mapped flood zones |
The county building inspector verifies compliance with code. That is a public function, not a service to you as the buyer, and code is a minimum standard rather than a quality standard. Budget for your own inspector.
The eleven month inspection is the one buyers most often skip and most often regret. Builder warranties typically have a first year period covering items that a later structural period does not, and the claim has to be made inside the window.
The floor plan is the same in every community. The lot is the part you cannot change, and in a community still building out it is the part with the most unknowns.
Ask these questions on any specific homesite in Wellen Park before you pay a lot premium.
What is planned for the parcel directly behind and beside this one. In an actively building community, today's open space is not necessarily tomorrow's open space. Ask for the current site plan and understand which parts are approved and which are conceptual.
Where does water go on this lot. Grading and drainage matter enormously in Southwest Florida, and a lot at the low point of a run collects water that lots uphill shed.
What is the flood zone for this specific parcel, and what is the finished floor elevation. Zone assignment is per parcel, not per community, and elevation drives your flood premium under FEMA Risk Rating 2.0.
What is the district assessment on this lot. In Wellen Park, district assessments trace back to the West Villages Improvement District structure and appear on your county tax bill. They are parcel-specific.
Which way does the lanai face. This sounds trivial and it is not. In this climate, a western exposure on an unshaded lanai changes how you use the house from March through October.
Incentives are usually attached to using the builder's affiliated lender or title company, and they are usually funded from margin the builder would otherwise give up on price. Model the incentive against a competing quote rather than accepting it at face value.
Incentive type | What it does | What to check |
|---|---|---|
Rate buydown | Reduces your interest rate, permanently or for an initial period | Whether the rate after a temporary buydown is one you can afford, and how the affiliated lender's fees compare |
Closing cost credit | Reduces cash needed at closing | Whether the credit is conditioned on using the affiliated lender or title company |
Design center allowance | Credit toward finishes and upgrades | What the design center charges relative to aftermarket pricing for the same work |
Included upgrades | Specific features at no additional cost | Whether you actually want them, and what they would cost separately |
Lot premium waiver | Reduces the premium on a specific homesite | Why that particular lot is being discounted |
You are generally allowed to compare. Get a quote from an outside lender and compare the total cost, including fees and the rate, against the builder's affiliated lender with the incentive applied. Sometimes the incentive wins clearly. Sometimes it does not. You will not know without the comparison.
Incentive programs change frequently, often month to month and by community. We do not publish current incentive figures for that reason. Ask what is available on the specific homesite this week, in writing.
Insurance, the district assessment, the HOA budget and the contract's cancellation terms. All four are knowable early, and all four are expensive to discover late.
Get a written insurance quote on the planned structure, not an estimate. New construction generally underwrites more favorably than older housing stock here, because roof age, construction type and wind mitigation features drive the premium. That is a real advantage, but confirm it in writing rather than assuming it.
Pull the district assessment for the exact parcel from the Sarasota County tax roll. Read the HOA budget and, where applicable, the reserve funding. And read the deposit and cancellation language in the builder agreement carefully, ideally with a Florida real estate attorney, before the money is committed.
You are not required to have one, but you should, and you should register your representation on your first visit to any sales center. The consultant in the model home is a licensed professional employed by or working for the builder, and they represent the builder's interests. Independent representation reviews the builder agreement, checks the parcel-level district assessment, orders your own inspections and compares the incentive against an outside lender quote. In almost every case it costs the buyer nothing additional, and some builders will not recognize an agent brought in after an unrepresented first visit.
Yes, and two of them. Order a pre-drywall inspection while framing, plumbing, electrical and mechanical work are still visible, and a full inspection before closing. The county building inspector verifies code compliance, which is a minimum standard and a public function rather than a service performed on your behalf. Add an eleven month warranty inspection before the first year warranty period expires, because that is when settlement and system issues surface and while they are still the builder's responsibility to correct.
Yes. Homes in Wellen Park carry district assessments that trace back to the West Villages Improvement District structure. They appear on your annual Sarasota County property tax bill rather than your HOA invoice, which is why buyers who budget from the mortgage estimate alone miss them. The assessment is parcel-specific and typically has a debt service component that eventually retires and an operations and maintenance component that does not. Pull the current figure for the exact lot from the county tax roll before your deposit becomes non-refundable.
Sometimes clearly yes, sometimes no, and you cannot tell without comparing. Builder incentives are usually conditioned on using an affiliated lender or title company, and they are funded from margin the builder would otherwise concede on price. Get a written quote from an independent lender covering the rate and all fees, then compare total cost against the affiliated lender with the incentive applied. Also check whether a temporary rate buydown resets to a payment you can still afford. Incentive terms change frequently, so get them in writing for your specific homesite.
Base price is usually the hardest thing to move, because builders protect published pricing to avoid affecting appraisals and the value of homes already sold in the community. Incentives, upgrades, lot premiums and closing cost contributions are where the flexibility usually sits. Standing inventory and completed spec homes generally carry more room than a home you are starting from scratch, particularly near the end of a builder's quarter. Ask what is available on that specific home, this week, in writing.
Beyond Realty reads the builder agreement, pulls the district assessment from the Sarasota County tax roll, reviews the HOA budget, orders independent pre-drywall and final inspections, and gets a written insurance quote, before your deposit becomes non-refundable.
Nothing here is legal advice, and a Florida real estate attorney should review any builder contract you are unsure about. Beyond Realty is based in downtown Sarasota and works across Sarasota, Manatee and Charlotte counties, including Wellen Park, North Port, Venice, Nokomis, Lakewood Ranch, Waterside and Palmer Ranch. Get in touch or read more about Darren Dowling.
Darren Dowling, Founder Beyond Realty 2170 Main Street, Suite 103 Sarasota, FL 34237 (941) 204-0493
How VA Home Loan Benefits, More Negotiating Opportunities, and Local Real Estate Market Conditions Could Help Veterans and Active-Duty Service Members Buy a Home in Sa… Read more
What Buyers and Sellers Need to Know About Mortgage Rates, Home Values, and Real Estate Market Trends in Sarasota, Lakewood Ranch, Manatee County, and Charlotte County.
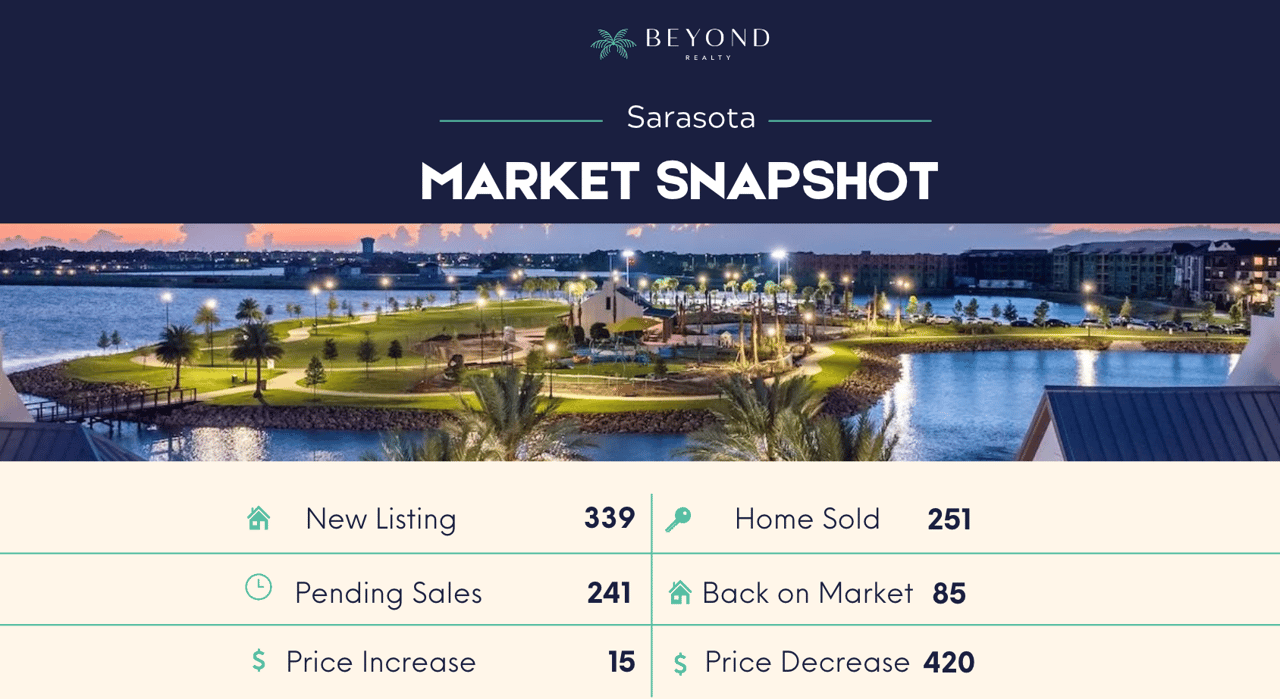
Closed Sales and Pending Activity Rise in Sarasota County as Pricing Adjustments Continue Across Both Markets
You’ve got questions and we can’t wait to answer them.