Why Southwest Florida Is Still One of the Best Places to Retire in 2026
Darren Dowling

Darren Dowling
Southwest Florida still ranks among the best places to retire in 2026 because Sarasota, Manatee and Charlotte counties combine no Florida income tax, the homestead exemption with the Save Our Homes 3 percent cap, and hospital access at Sarasota Memorial, Lakewood Ranch Medical Center and Fawcett Memorial. County choice drives taxes and care.
Yes, and the reason is structural rather than seasonal. Florida has no state individual income tax, the homestead exemption and Save Our Homes cap protect long term owners from assessment spikes, and the Sarasota to Punta Gorda corridor has three established hospital systems rather than one. Those advantages do not expire when the market cools.
What has changed is that the decision is now about carrying cost rather than purchase price. Insurance, flood zone, and Community Development District assessments vary enormously between two homes at the same price, sometimes on the same street. Retirees who shop on list price alone are the ones who get surprised.
The county line is the single most consequential choice you make, because it sets your property tax millage, your school district, your hospital network and the clerk's office where you file your Declaration of Domicile and homestead exemption.
Sarasota County covers Downtown Sarasota (34236), Siesta Key (34242), Palmer Ranch (34238), Osprey, Nokomis, Venice and the Waterside side of Lakewood Ranch (34240). Manatee County covers Bradenton, Parrish, Palmetto, Anna Maria Island and most of Lakewood Ranch (34202, 34211, 34212). Charlotte County covers Port Charlotte, Punta Gorda and Punta Gorda Isles.
Factor | Sarasota County | Manatee County | Charlotte County |
|---|---|---|---|
Main retiree hubs | Venice, Palmer Ranch, Osprey, Siesta Key | Lakewood Ranch, Parrish, Bradenton | Punta Gorda, Punta Gorda Isles, Port Charlotte |
Primary hospital | Sarasota Memorial, Sarasota and Venice campuses | Lakewood Ranch Medical Center, HCA Florida Blake | Fawcett Memorial, Port Charlotte |
Beach access | Siesta Key, Lido Key, Venice beaches | Anna Maria Island, Longboat Key north end | Boca Grande and Gulf access via Charlotte Harbor |
Boating character | Gulf passes, Intracoastal | Tampa Bay and Intracoastal | Charlotte Harbor and Peace River, deep canal networks |
Typical entry cost | Highest of the three | Middle, varies sharply by ZIP | Generally the most accessible |
Homestead filed with | Sarasota County Property Appraiser | Manatee County Property Appraiser | Charlotte County Property Appraiser |
Millage rates differ between these counties and between incorporated cities and unincorporated areas within them. Beyond Realty pulls the current certified millage for the specific parcel rather than quoting a countywide average, because an average is not what appears on your bill.
Your savings equal what your former state would have taxed on your particular income mix, minus Florida's higher insurance cost and any CDD assessment on the home you buy. There is no single dollar figure, because the answer depends on whether your income is pension, Social Security, IRA withdrawals, capital gains or earned income.
Florida has no state individual income tax and no state estate or inheritance tax. For a retiree drawing a taxable pension and making IRA withdrawals, that is the largest single line item of the move. For a retiree whose income is mostly Social Security, the benefit is smaller, because several states already exempt Social Security.
The move is not automatic. Changing your tax home means changing your domicile, which generally includes filing a Declaration of Domicile with the Clerk of the Circuit Court in your new county, applying for homestead exemption, registering to vote, and obtaining a Florida driver license and vehicle registration. High tax states do audit this, and the burden of proof sits with you.
Florida's homestead exemption reduces the assessed value of your primary residence, and the Save Our Homes provision then caps annual increases in that assessed value at 3 percent or the change in the Consumer Price Index, whichever is lower. The benefit compounds for as long as you hold the homestead.
Two practical points retirees miss. First, homestead applies only to your primary residence, so a seasonal second home does not qualify, and claiming it on a home that is not your permanent residence creates real exposure. Second, Florida allows portability, meaning an established Save Our Homes benefit can be carried to a new Florida homestead within statutory limits. A retiree downsizing within Sarasota County, for example, may be able to move accumulated benefit rather than starting over.
Filing deadlines and documentation requirements are set by each county property appraiser. Confirm the current year's deadline with the appraiser for your county rather than relying on a general article.
Southwest Florida has two distinct products: true 55 plus communities that are deed restricted under the Housing for Older Persons Act, and all ages master planned communities that simply happen to attract many retirees. They are not interchangeable, and marketing language frequently blurs the two.
Community | County | Character | Age restricted? |
|---|---|---|---|
Del Webb Lakewood Ranch | Manatee | Gated, amenity centered, Del Webb brand | Marketed as 55 plus, confirm in documents |
Cresswind Lakewood Ranch | Manatee | Gated, active adult positioning | Marketed as 55 plus, confirm in documents |
Del Webb Bay View, Parrish | Manatee | Newer, north county, lower entry | Marketed as 55 plus, confirm in documents |
IslandWalk, Wellen Park | Sarasota | Large amenity base, strong retiree share | All ages, verify |
Sarasota National, Venice | Sarasota | Golf and nature preserve setting | All ages, verify |
Grand Palm, Venice | Sarasota | Neal Communities, extensive trails | All ages, verify |
Punta Gorda Isles | Charlotte | Canal homes, sailboat and powerboat access | All ages, verify |
Babcock Ranch | Charlotte and Lee | Planned, solar, town center | All ages, verify |
Treat every entry in that last column as a question to be answered in writing from the recorded declaration, not from a sales center conversation. Age restriction, rental rules, pet limits and whether golf membership is bundled or optional all live in the governing documents.
Hospital access in this corridor is genuinely strong, but Medicare Advantage networks are county and plan specific, so a plan that works well in your current state may have no usable Florida network at all. Original Medicare travels nationwide to any participating provider. Medicare Advantage often does not.
The anchors are Sarasota Memorial Health Care System, with its main campus in ZIP 34239 and a Venice campus, Lakewood Ranch Medical Center, HCA Florida Blake Hospital in Bradenton, and Fawcett Memorial Hospital in Port Charlotte.
Three practical steps before you close:
Drive time, not map distance, is the number that matters here. Seasonal traffic on Clark Road, University Parkway and US 41 changes travel times materially between the quiet months and the peak months.
Four line items decide whether a Southwest Florida retirement budget holds: property tax at the parcel's actual millage, windstorm and hazard insurance, flood insurance if the parcel sits in a FEMA mapped zone, and any CDD assessment attached to the lot.
Cost line | What drives it | Why retirees get surprised |
|---|---|---|
Property tax | Certified millage for that parcel, plus assessed value after homestead | Prior owner's long held Save Our Homes cap resets for you |
Windstorm and hazard insurance | Roof age, construction type, wind mitigation features, distance to coast | Quoted before the roof age is verified |
Flood insurance | FEMA zone X, AE or VE, and Risk Rating 2.0 inputs | Zone X is not a guarantee of no flood risk or no lender requirement |
CDD assessment | Whether the community was financed through a Community Development District | Appears on the tax bill, not in the HOA statement, so it gets missed |
HOA and club dues | Governing documents, bundled versus optional golf | Bundled golf can be mandatory and non negotiable |
A CDD is a special district that finances community infrastructure and collects assessments through the annual tax bill. It is separate from the HOA. Two otherwise identical homes, one inside a CDD and one outside, can carry meaningfully different annual costs. This is a per parcel fact, and it is verifiable before you write an offer.
The most expensive mistakes are budgeting from the seller's current tax bill, assuming flood zone X means no flood exposure, and taking age restriction or golf obligations on trust from a sales center.
The seller's tax bill reflects their accumulated Save Our Homes cap, which does not transfer to you. Your assessed value generally resets, so the bill you inherit can be substantially higher than the one you saw. Flood zone X means the parcel is outside the high risk mapped area, which affects lender requirements, not physical risk, and Risk Rating 2.0 prices risk by property characteristics rather than by zone alone. And bundled golf, where club membership and dues are mandatory conditions of ownership, is a long term obligation that is easy to misread as optional.
Florida levies no state individual income tax, so Social Security benefits, pension income, and IRA and 401(k) withdrawals are not taxed at the Florida state level. Federal income tax still applies exactly as it does anywhere else in the United States, and required minimum distribution rules do not change. Florida also has no state estate or inheritance tax. How much you actually save depends on how your former state treated each income type, since several states already exempt Social Security and some partially exempt pension income.
Millage rates vary by county and also by whether a parcel sits in an incorporated city or an unincorporated area, so there is no single ranking that stays accurate. Charlotte County generally offers the lowest entry prices of the three, which lowers the taxable base, but the millage rate itself is a separate question from price. The honest answer is to compare the certified millage for the two or three specific parcels you are considering. Beyond Realty pulls that figure per parcel rather than quoting a countywide average.
Several Southwest Florida communities with large retiree populations are all ages rather than deed restricted, and marketing language often implies otherwise. True age restricted communities operate under the Housing for Older Persons Act and state the restriction in their recorded governing documents. Communities such as Del Webb Lakewood Ranch and Del Webb Bay View are marketed as 55 plus, while IslandWalk, Grand Palm and Sarasota National are generally all ages. Always confirm age restriction from the recorded declaration before you rely on it, not from a brochure or a sales center conversation.
Not necessarily. Medicare Advantage plans are built around county level provider networks, so a plan that serves you well in another state may have no usable network here. Original Medicare travels nationwide and is accepted by any participating provider, which is why many relocating retirees review their coverage before moving rather than after. Confirm in writing whether your specific plan operates in your target county and whether Sarasota Memorial, Lakewood Ranch Medical Center, HCA Florida Blake or Fawcett Memorial participates, along with any specialists you see regularly.
Flood zone X means FEMA has mapped the parcel outside the high risk special flood hazard area, so a federally backed lender generally will not require flood insurance there. That is a lending requirement, not a statement that the property cannot flood. Under Risk Rating 2.0, FEMA prices flood risk using property specific characteristics such as elevation, distance to water and replacement cost rather than zone alone, so premiums vary within the same zone. Many owners in zone X carry coverage voluntarily. Verify the current mapped zone for the exact parcel before budgeting.
Beyond Realty verifies these facts per parcel before you write an offer, because every one of them is address specific rather than community wide. That means pulling the certified millage for the parcel, confirming the FEMA mapped flood zone, identifying whether a CDD assessment applies and what the remaining term looks like, and reading the recorded governing documents for age restriction, rental rules and whether golf or club membership is mandatory.
Darren Dowling is the Broker-Owner of Beyond Realty and works with retirees relocating into Sarasota, Manatee and Charlotte counties. If you want these items checked for specific addresses you are considering, get in touch or read more about Darren.
Darren Dowling, Broker-Owner, Beyond Realty, 2170 Main Street, Suite 103, Sarasota, FL 34237, (941) 204-0493.
How VA Home Loan Benefits, More Negotiating Opportunities, and Local Real Estate Market Conditions Could Help Veterans and Active-Duty Service Members Buy a Home in Sa… Read more
What Buyers and Sellers Need to Know About Mortgage Rates, Home Values, and Real Estate Market Trends in Sarasota, Lakewood Ranch, Manatee County, and Charlotte County.
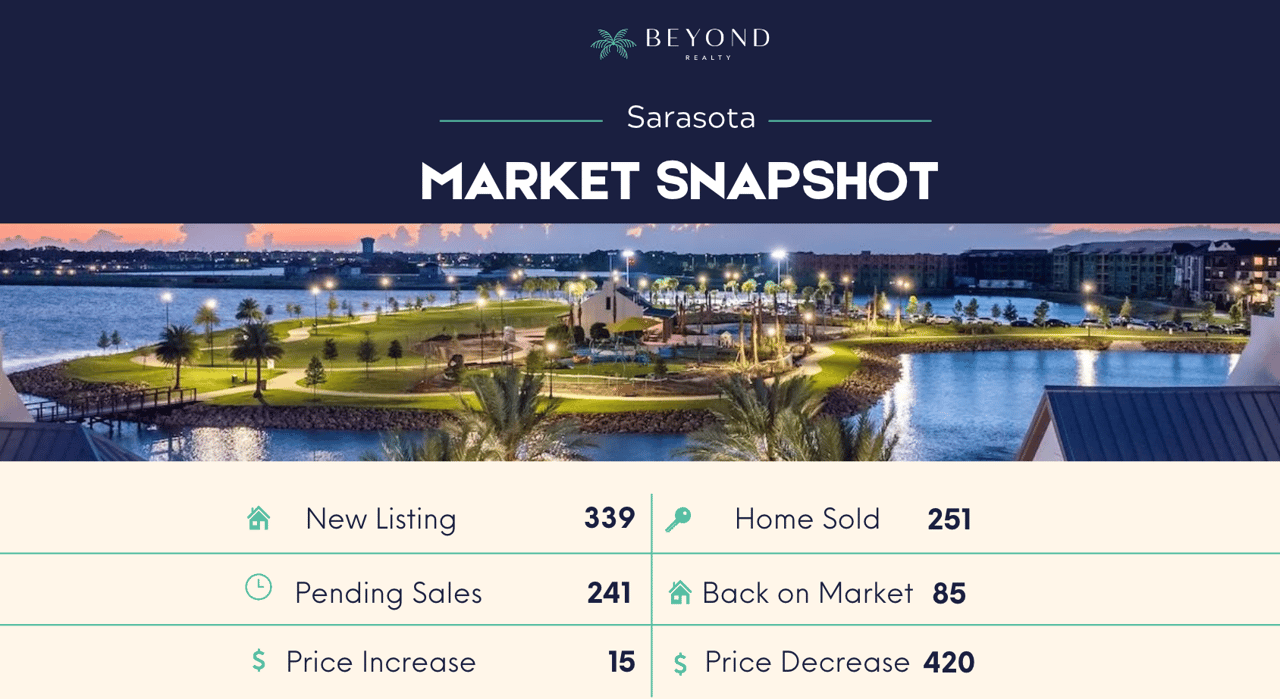
Closed Sales and Pending Activity Rise in Sarasota County as Pricing Adjustments Continue Across Both Markets
You’ve got questions and we can’t wait to answer them.