How to Use Your Tax Refund to Buy a Home in Sarasota and Lakewood Ranch
Darren Dowling

Darren Dowling
A tax refund is most useful in Sarasota and Lakewood Ranch as earnest money, inspection costs and prepaid insurance, not just down payment. FHA allows 3.5 percent down, conventional loans start near 3 percent, and VA and USDA allow zero down in eligible areas like parts of North Port.
Key takeaways:
Most buyers assume a refund goes to the down payment. In practice the refund is more valuable covering the cash you have to spend before you ever reach the closing table. Down payment money can come from a loan program with a low minimum. Earnest money and inspection fees cannot.
Where the refund can go | Why it matters in Sarasota and Lakewood Ranch | Timing |
|---|---|---|
Earnest money deposit | A stronger deposit makes a weaker offer price more credible to a seller | At contract |
Home inspection and wind mitigation inspection | A wind mitigation report can lower your insurance premium, and it pays for itself often | Inspection period |
Four point inspection on older homes | Many carriers require one on homes past a certain age before they will quote | Inspection period |
Survey and elevation certificate | An elevation certificate can change a flood quote materially on coastal parcels | Before closing |
Prepaid insurance and escrow | Florida carriers commonly want the first year paid at or before closing | At closing |
Down payment | Can be as low as 3 to 3.5 percent on common programs, or zero on VA and USDA | At closing |
Rate buydown points | Worth modeling against how long you will actually hold the loan | At closing |
Post closing reserve | The least exciting and often the smartest use | After closing |
The last row deserves emphasis. Arriving at closing with nothing left is how new owners end up financing a water heater on a credit card. A reserve is not a wasted refund.
You do not need 20 percent. Common programs start at zero to 3.5 percent, and the right one depends on your service history, the property type and the address. The 20 percent figure persists because it avoids mortgage insurance, not because lenders require it.
Program | Minimum down | Notes for this market |
|---|---|---|
VA | Zero for eligible veterans and service members | No monthly mortgage insurance, funding fee applies, strong option here |
USDA Rural Development | Zero in designated eligible areas | Eligibility is set by address, and parts of eastern Manatee County, North Port and the Myakka area can qualify |
FHA | 3.5 percent | More flexible credit, mortgage insurance for the life of most loans, condo project must be approved |
Conventional | Commonly 3 to 5 percent for qualified buyers | Private mortgage insurance drops off at a set equity threshold |
Conventional 20 percent | 20 percent | No mortgage insurance, lowest monthly payment, largest cash requirement |
Two Sarasota specific cautions. Condominium financing depends on the project as well as the borrower: FHA requires an approved condo project, and conventional lenders review the association's budget, reserves and litigation. And in a market where insurance can swing by a large margin between two similar homes, the loan program you qualify for matters less than whether the total payment, including insurance and any assessment, actually fits.
Florida charges transfer taxes that buyers from other states do not expect, and they are calculated on the deed and on the mortgage separately. Budget for them in cash, because they are not financed.
Line item | How it is calculated | Who typically pays in this area |
|---|---|---|
Documentary stamp tax on the deed | 70 cents per 100 dollars of the sale price outside Miami-Dade | Customarily the seller in this area, but it is negotiable |
Documentary stamp tax on the note | 35 cents per 100 dollars of the amount financed | The buyer |
Intangible tax on the mortgage | 2 mills, or 0.002, of the amount financed | The buyer |
Title insurance | Based on the policy amount | Varies by county custom and by negotiation |
Prepaid property insurance | The carrier's first year premium | The buyer |
Property tax proration | Based on the closing date | Split at closing |
HOA or condo estoppel and transfer fees | Set by the association | Usually the buyer, verify in the contract |
CDD assessment proration | Based on the closing date and the lot | Split at closing |
The two stamp and intangible lines are the ones out of state buyers forget. On a typical mortgage they are not trivial, and they are due at closing in certified funds.
Yes, and they change. Florida Housing Finance Corporation runs statewide assistance programs, and Sarasota County and Manatee County have operated their own local programs over the years. Funding and eligibility rules move, which is why no honest guide should quote you an amount.
What tends to be true across these programs: there is an income limit, there is a purchase price limit, you usually must complete a homebuyer education course, the property must be your primary residence, and assistance often arrives as a second mortgage that is deferred, forgivable over time, or repayable at sale or refinance. Florida Housing has also run the Hometown Heroes program for eligible frontline workers.
Check current availability and funding status directly with Florida Housing and with the county housing office before you plan around any of it. Beyond Realty will point you to the current programs and connect you with lenders who actually originate them, which is a shorter list than you would expect.
Lenders document the source of funds, and a large deposit that appears without explanation can delay or derail an approval. A tax refund is one of the easiest deposits to document, which is an advantage.
Keep the deposit clean. Let the refund land in the account you will use for the purchase, keep the deposit intact rather than moving it between accounts, and keep a copy of your return and the deposit record. Avoid cash deposits in the same period, because cash cannot be sourced and underwriters will simply exclude it. If family is gifting part of your funds, that needs a gift letter and its own paper trail, which is a separate process from the refund.
Step | What to do |
|---|---|
Refund arrives | Deposit it into the account you will use for the purchase, and leave it there |
Get pre approved | Give the lender the statement showing the deposit, with your return as backup |
Write the offer | Use part of the refund for earnest money, held per the contract |
Inspection period | Spend on inspection, wind mitigation and, where relevant, four point and elevation |
Before closing | Bind insurance and fund prepaids |
At closing | Bring certified funds for the balance of cash to close |
Model both against how long you will actually keep the loan, not against a thirty year horizon you will probably not reach. Buying points lowers your payment but takes years to break even, and refinancing or selling before that point wastes the money.
A larger down payment reduces the loan amount, which reduces the Florida intangible tax and note stamps as well as the interest. A buydown reduces the rate for a period or for the life of the loan depending on structure. For buyers who expect to hold the home for a long time and have cash beyond the reserve, points can win. For buyers who may move or refinance within a few years, the reserve usually wins. Ask your lender for a side by side with a break even month on it, in writing.
If you want the cash to close mapped on a specific home, including insurance, the stamp and intangible taxes and any CDD proration, contact Beyond Realty. You can also read more about Darren Dowling, Broker-Owner.
Often it is enough for part of it, and sometimes for all of it depending on the program and the price point. FHA requires 3.5 percent down, common conventional programs start near 3 percent for qualified buyers, and VA and USDA allow zero down for eligible borrowers and eligible addresses. The more useful question is whether the refund covers the cash that comes before closing: earnest money, inspections and prepaid insurance. Those cannot be financed, and in this market the insurance prepay is frequently the largest of them.
They are state transfer taxes charged on the transaction. The documentary stamp tax on the deed is 70 cents per 100 dollars of consideration outside Miami-Dade, and in this area it is customarily paid by the seller, though it is negotiable. The buyer typically pays the documentary stamp tax on the note, 35 cents per 100 dollars financed, and the intangible tax on the mortgage, 2 mills or 0.002 of the amount financed. Both buyer side items are due at closing in certified funds and cannot be rolled into the loan.
You are not required to get one, but it is usually worth the cost. A wind mitigation inspection documents roof shape, roof deck attachment, roof to wall connections and opening protection, and Florida carriers apply credits based on what it shows. On a home with favorable construction, those credits can reduce the premium enough to pay for the inspection many times over. On older homes, you may also need a four point inspection covering roof, electrical, plumbing and HVAC before a carrier will quote at all.
Yes, and they change with funding cycles. Florida Housing Finance Corporation runs statewide down payment and closing cost assistance, including the Hometown Heroes program for eligible frontline workers, and Sarasota County and Manatee County have operated their own local assistance programs. Expect income limits, purchase price limits, a homebuyer education requirement and a primary residence requirement. Assistance is commonly structured as a deferred or forgivable second mortgage. Verify current availability and funding directly with Florida Housing and the county before planning around it.
It depends on your carrying cost, not on a market forecast. Run the actual monthly number on a specific property, including principal, interest, taxes after the assessed value resets, insurance with a real quote, and any HOA dues or CDD assessment. If that number works today with a reserve left over, waiting mainly costs you rent and time. If it only works by spending your reserve, waiting is the right call regardless of what prices do. Beyond Realty will run that math on a real parcel rather than a generic estimate.
Darren Dowling, Broker-Owner, Beyond Realty, 2170 Main Street, Suite 103, Sarasota, FL 34237, (941) 204-0493.
How VA Home Loan Benefits, More Negotiating Opportunities, and Local Real Estate Market Conditions Could Help Veterans and Active-Duty Service Members Buy a Home in Sa… Read more
What Buyers and Sellers Need to Know About Mortgage Rates, Home Values, and Real Estate Market Trends in Sarasota, Lakewood Ranch, Manatee County, and Charlotte County.
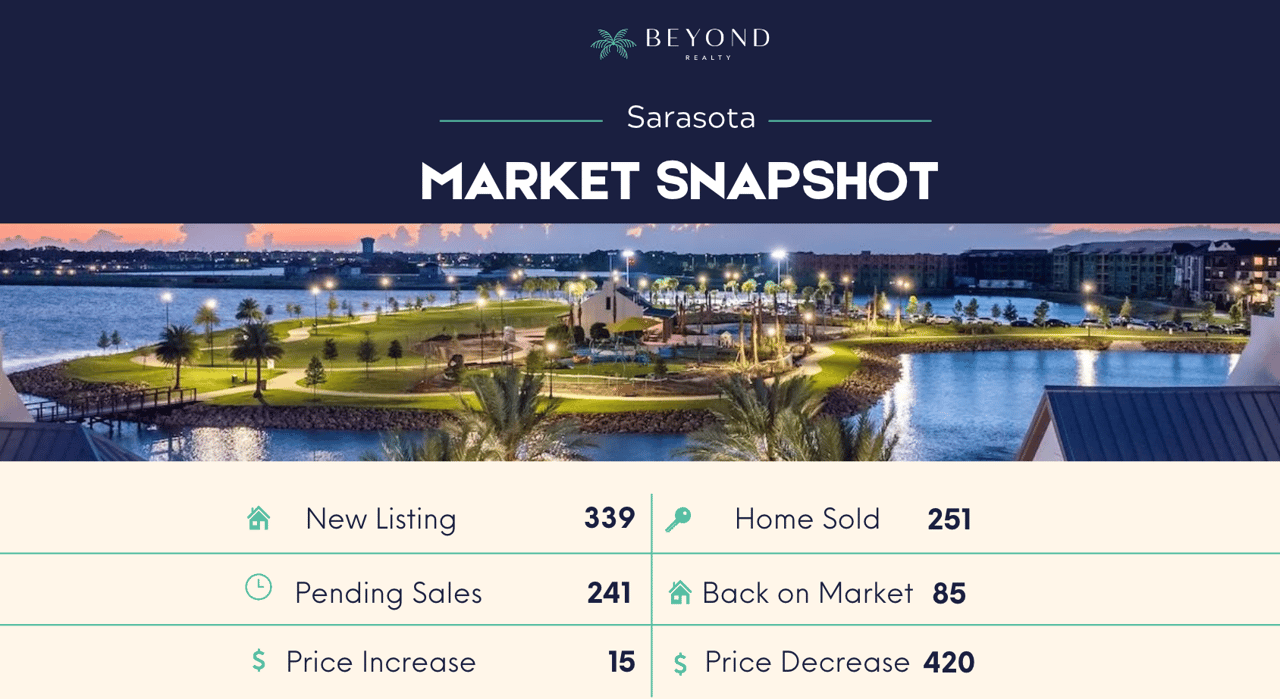
Closed Sales and Pending Activity Rise in Sarasota County as Pricing Adjustments Continue Across Both Markets
You’ve got questions and we can’t wait to answer them.