Think You Need 20% Down to Buy a Home in Sarasota? Think Again
Darren Dowling

Darren Dowling
You do not need 20 percent down to buy in Sarasota, Lakewood Ranch, Venice or North Port. FHA allows as little as 3.5 percent, VA and USDA allow zero down for those who qualify, and Florida Housing plus county SHIP programs offer assistance. Insurance and CDD costs matter more than your down payment size.
Key takeaways
No. A 20 percent down payment eliminates private mortgage insurance on a conventional loan, which lowers your monthly payment. It has never been a requirement to purchase. Waiting to reach 20 percent while prices, rates and rents move is a decision with its own cost, and that cost is rarely calculated.
The right question is not how much you need. It is what each option costs you per month, over how long, and what you give up in reserves.
Loan type | Minimum down payment | Mortgage insurance | Who it suits |
|---|---|---|---|
Conventional | As low as 3 percent for qualifying first-time buyers, commonly 5 percent | Private mortgage insurance, which can be removed once you reach sufficient equity | Buyers with solid credit who want a path off mortgage insurance |
FHA | 3.5 percent with qualifying credit | FHA mortgage insurance premium, which on most current loans stays for the life of the loan | Buyers with lower credit scores or thinner credit history |
VA | Zero down for eligible veterans, active duty and certain surviving spouses | No monthly mortgage insurance, but a VA funding fee usually applies | Anyone eligible. Generally the strongest option available |
USDA | Zero down in eligible rural and suburban areas | Guarantee and annual fees apply | Buyers targeting eligible areas, which include parts of Manatee, Sarasota and Charlotte counties |
Conventional with 20 percent down | 20 percent | None | Buyers with the cash who value the lowest monthly payment |
USDA eligibility is drawn on a map and it is revised. Do not assume a neighborhood qualifies or does not. Check the specific address.
Assistance in Florida comes from two directions: statewide programs administered by Florida Housing Finance Corporation, and local programs each county funds through the State Housing Initiatives Partnership, known as SHIP.
Source | What it generally offers | Where to verify current terms |
|---|---|---|
Florida Housing Finance Corporation | First mortgage programs paired with down payment and closing cost assistance, often as a second mortgage | Florida Housing, or a Florida Housing approved participating lender |
Sarasota County SHIP | Locally administered purchase assistance for income-qualified buyers | Sarasota County housing office |
City of Sarasota | Municipal housing programs for buyers within city limits | City of Sarasota housing division |
Manatee County SHIP | Locally administered purchase assistance for income-qualified buyers | Manatee County housing office |
Charlotte County SHIP | Locally administered purchase assistance for income-qualified buyers | Charlotte County housing office |
Employer and profession-specific programs | Assistance targeted at specific occupations | Your employer's benefits office and Florida Housing |
Lender and builder incentives | Rate buydowns, closing cost credits, occasionally down payment help | The specific lender or builder, in writing |
Two honest cautions. First, these programs have income limits, purchase price caps, occupancy requirements and, in many cases, repayment or forgiveness terms tied to how long you stay. Second, program funding is periodically exhausted and then replenished, and terms change between funding cycles. We do not publish dollar figures or income limits here, because a number that is right today will be wrong within a year. Confirm current terms directly with the administering agency or an approved lender.
Enough to get the loan you want without draining your reserves, because Southwest Florida carrying costs are front loaded. Insurance, HOA dues, a CDD assessment and your first tax bill all arrive before your first year is out.
Consideration | Argues for a larger down payment | Argues for a smaller down payment |
|---|---|---|
Monthly payment | Lower principal and interest, and no mortgage insurance at 20 percent | Higher payment, but you keep cash |
Cash reserves | Less cushion after closing | More cushion for insurance, repairs and the first tax bill |
Insurance surprises | Less room to absorb a higher than expected premium | More room to absorb it |
Roof or system replacement | Less liquidity for a major repair | More liquidity |
Competing offers | A larger down payment can read as a stronger offer to some sellers | Proof of funds and a clean contract matter more than the percentage |
Rate environment | Less balance exposed to the rate | A buydown or credit may do more for your payment than extra down payment |
The mistake we see most often is a buyer who puts every available dollar into the down payment, closes, and then receives an insurance renewal or a special assessment with nothing left to absorb it. In this market, reserves are not a luxury.
Four line items that do not appear on a listing portal: homeowners insurance, flood insurance where required, HOA and sub-association dues, and the CDD assessment in master-planned communities.
Homeowners insurance here is underwritten on the individual structure, using roof age and material, construction type, wind mitigation features, flood zone, elevation, distance to water and replacement cost. Two homes in the same ZIP code can be quoted very differently. Get a live quote on the specific address during your inspection period rather than budgeting from an average.
A Community Development District assessment finances the roads, drainage, utilities and amenities in master-planned communities such as Lakewood Ranch, Waterside, Skye Ranch and Wellen Park. It appears on your annual county property tax bill, not your HOA invoice. It typically has a debt service portion that eventually retires and an operations and maintenance portion that does not. Amounts are parcel-specific.
And your first property tax bill will not match the seller's. Florida's Save Our Homes cap limits assessed value growth for homesteaded owners, and that assessed value resets on transfer. Ask for a county property appraiser estimate at your purchase price.
Get preapproved before you tour, not after you fall in love with a house. In a market where insurance can change the math, a preapproval that ignores insurance and CDD is not a real number.
Step | What happens | What to insist on |
|---|---|---|
1. Talk to a Florida lender | Review credit, income, assets and eligibility for VA, USDA and assistance programs | A lender who prices insurance and CDD into the payment estimate |
2. Get preapproved | Written preapproval, not a prequalification text message | An amount you are comfortable with, not the maximum you qualify for |
3. Set your search parameters | Price, area, property type, HOA tolerance | A monthly cost target rather than a purchase price target |
4. Tour and write | Offer with a defined inspection period | Enough inspection time to get an insurance quote back |
5. Inspection period | Home inspection, wind mitigation, flood determination, HOA and CDD verification, insurance quote | All of it completed before the period expires |
6. Appraisal and underwriting | Lender conditions, appraisal contingency | Prompt document turnaround, because delays cost you leverage |
7. Close, then file homestead | Closing, then your exemption filing | The March 1 homestead deadline on your calendar |
Do not let the inspection period lapse while waiting on an insurance quote. That is the most common way a first-time buyer here loses the ability to renegotiate or walk.
It depends on the loan. VA loans allow zero down for eligible veterans, active duty service members and certain surviving spouses. USDA loans allow zero down on eligible properties, and parts of Manatee, Sarasota and Charlotte counties fall inside eligible areas. FHA allows as little as 3.5 percent with qualifying credit. Some conventional programs allow as little as 3 percent for qualifying first-time buyers. There is no single Sarasota minimum, because it is set by the loan program and your qualifications, not by the local market.
Yes. Assistance comes from two directions. Florida Housing Finance Corporation administers statewide programs that pair a first mortgage with down payment and closing cost help. Separately, Sarasota County, Manatee County and Charlotte County each administer local assistance funded through the State Housing Initiatives Partnership program, and the City of Sarasota runs its own programs for buyers inside city limits. All of them carry income limits, purchase price caps and occupancy requirements, and funding runs in cycles. Confirm current terms with the administering agency or an approved lender.
Less than most buyers assume. Sellers care about certainty of closing, and that comes from a strong preapproval, proof of funds, a realistic timeline and clean terms, not from the down payment percentage on its own. A well-documented buyer putting 5 percent down with a solid lender often presents better than a buyer putting 20 percent down with a vague prequalification. Where a larger down payment genuinely helps is on a property with appraisal risk, because more cash gives you room to bridge a low appraisal.
There is no universal answer, and anyone who gives you one is selling something. Waiting builds your down payment and your reserves. It also exposes you to price movement, rate movement and continued rent. The honest way to decide is to run both scenarios with a lender using your actual numbers, including insurance and any CDD assessment, and compare total cost over the period you expect to own. Do not decide from a national headline. This market has its own cost structure.
On a conventional loan, generally yes. Once you reach sufficient equity, you can typically request cancellation, and it terminates automatically at a defined point under federal rules. On most current FHA loans, by contrast, the mortgage insurance premium remains for the life of the loan, which is why some buyers refinance out of FHA into conventional once they have equity. VA loans have no monthly mortgage insurance at all, though a funding fee usually applies at closing. Ask your lender to model the total cost of each path, not just the starting payment.
Beyond Realty pulls the CDD assessment from the county tax roll, the HOA dues and reserves from the association documents, the flood determination from the FEMA map and a live insurance quote from a carrier, then works with your lender so the payment estimate reflects all of it.
Nothing in this article is lending advice, and loan program terms are set by lenders and agencies rather than by us. Beyond Realty is based in downtown Sarasota and works across Sarasota, Manatee and Charlotte counties, including Lakewood Ranch, Waterside, Palmer Ranch, Venice, Nokomis, Osprey, Bradenton, North Port and Wellen Park. Get in touch or read more about Darren Dowling.
Darren Dowling, Founder Beyond Realty 2170 Main Street, Suite 103 Sarasota, FL 34237 (941) 204-0493
How VA Home Loan Benefits, More Negotiating Opportunities, and Local Real Estate Market Conditions Could Help Veterans and Active-Duty Service Members Buy a Home in Sa… Read more
What Buyers and Sellers Need to Know About Mortgage Rates, Home Values, and Real Estate Market Trends in Sarasota, Lakewood Ranch, Manatee County, and Charlotte County.
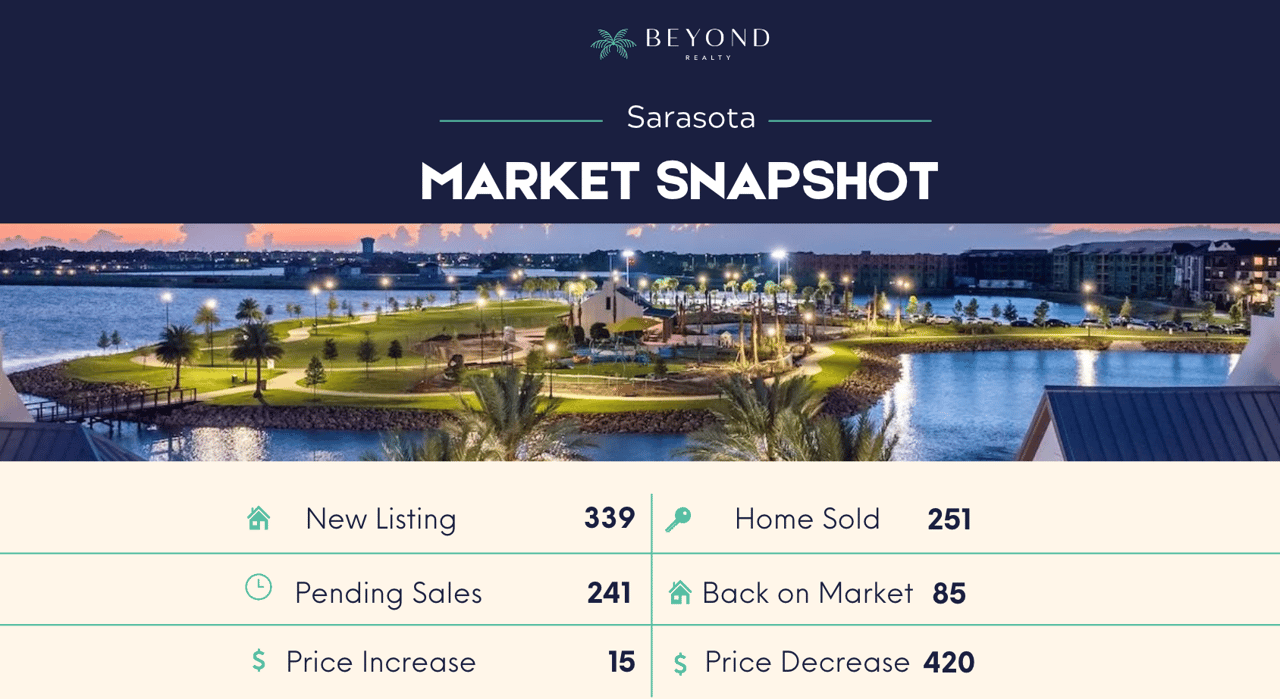
Closed Sales and Pending Activity Rise in Sarasota County as Pricing Adjustments Continue Across Both Markets
You’ve got questions and we can’t wait to answer them.