Priced Out of the Sarasota Housing Market? A Condo or Townhome Could Be Your Best Path to Homeownership
Darren Dowling, Broker-Owner, Beyond Realty
Darren Dowling, Broker-Owner, Beyond Realty
Condos and townhomes are the lowest-priced way into Sarasota, Lakewood Ranch, Venice and Punta Gorda, but they are not the same product. A townhome is usually fee simple ownership of the lot. A condo is ownership of the interior only, and in Florida that now carries milestone inspection and reserve study obligations.
Key takeaways
The difference is what you hold title to, not how the building looks. Two attached homes on the same street can be legally different products with different lender treatment and different monthly costs.
Condominium | Townhome | Villa or paired villa | Single-family | |
|---|---|---|---|---|
What you own | Interior of the unit, plus an undivided share of common elements | The home and the lot beneath it, in most cases | Varies. Some are condos, some are fee simple with an HOA | The home and the lot |
Who owns the roof and exterior | The association | Usually you, sometimes the HOA by covenant | Depends on the recorded documents | You |
Governing association | Condominium association under Chapter 718 | Homeowners association under Chapter 720, in most cases | Depends on the form of ownership | HOA if one exists, often none |
Your insurance | Unit owner HO-6 policy, association carries the master policy | Usually a full HO-3 homeowners policy | Depends on the form of ownership | Full HO-3 homeowners policy |
Typical monthly association cost | Highest, because it covers structure, roof, insurance and reserves | Lower, usually landscaping and common area | Middle | Lowest or none |
Financing nuance | Lender must find the project eligible, not just you | Underwritten much like a single-family home | Depends on the form of ownership | Simplest |
The row that costs people money is the one about what the marketing name means. In this region, "villa" and "townhome" describe building style, not legal ownership. Before you write an offer, we read the recorded declaration and tell you which one you are actually buying.
Florida now requires milestone structural inspections and structural integrity reserve studies for condominium and cooperative buildings three stories or higher, and restricts associations from waiving reserves for the structural components those studies identify. For a buyer, that turns association finances from a mystery into a document set you can read.
The legislature has amended these requirements more than once since they were enacted, including changes to timelines and to how associations may fund the required reserves. Because the rules have moved, we confirm the current requirement and the specific association's compliance status rather than relying on what was true a year ago.
Practically, this has three effects on a Sarasota area condo purchase.
First, some buildings have issued special assessments to fund newly required reserves or repairs identified by a milestone inspection. Those assessments are disclosed, and who pays them is negotiable in the contract.
Second, monthly association fees in older buildings, particularly on the barrier islands and in the downtown Sarasota core, have risen in many cases. A low fee is not automatically good news. It can mean the reserve study has not been acted on yet.
Third, association financial health now affects loan approval. Conventional lenders apply project eligibility standards, and a project with significant deferred maintenance, litigation or underfunded reserves can become hard to finance. That constrains your buyer pool when you eventually sell, which is a resale risk as much as a purchase risk.
Request the full document package and read it during your inspection period, not after. The FAR/BAR contract and Florida condominium law both give you a defined window for exactly this purpose.
Document | What you are looking for | Why it matters |
|---|---|---|
Recorded declaration of condominium | Whether it is legally a condo, and what the association maintains | Determines your insurance, your maintenance and your lender treatment |
Current budget | Whether reserves are funded and what the line items actually are | An underfunded budget is a future assessment |
Reserve study and structural integrity reserve study | Remaining useful life of roof, structure, waterproofing and other components | Tells you what is coming and roughly when |
Milestone inspection report, where applicable | Findings, and whether repairs were completed | The single most important document for an older building |
Board minutes for at least the last twelve months | Discussion of assessments, litigation, insurance and repairs | Minutes tell you what the budget does not |
Master insurance certificate | Coverage limits, deductibles, wind and flood coverage | A high wind deductible becomes a unit owner assessment after a storm |
Rules on rentals, pets and vehicles | Minimum lease terms, approval process, restrictions | Affects both lifestyle and resale to investors |
Estoppel or association statement | Current dues, pending assessments, arrears | Confirms what you are actually walking into |
Beyond Realty orders and reviews this package for every condo purchase we handle. If an association cannot produce a current budget and a reserve study, that itself is information.
Compare total monthly carrying cost, not list price. A condo with a lower price and a higher association fee can cost more each month than a townhome that looks more expensive on the listing.
Cost line | Condominium | Townhome | Single-family |
|---|---|---|---|
Principal and interest | Lowest, tracks the lower price | Middle | Highest |
Property tax | Tracks assessed value, homestead applies to your primary residence | Same mechanics | Same mechanics |
CDD assessment, where applicable | Applies in master-planned districts such as Lakewood Ranch, Wellen Park and Skye Ranch | Same | Same |
Master or condo association fee | Highest, covers structure, roof, master insurance, reserves, often water | Lower, usually landscaping and common area | None, or a modest HOA |
Your own insurance | HO-6 unit owner policy, generally the lowest of the three | Full homeowners policy | Full homeowners policy |
Exterior maintenance | Included in the fee | Partly yours | Entirely yours |
Assessment risk | Special assessments are a real and quantifiable risk | Lower, but not zero | None from an association |
Run those seven lines on each specific property before you rank them. The answer often reverses the order buyers arrive with.
Attached housing serves three different buyers here: the first-time buyer who wants to stop renting, the seasonal owner who wants to lock the door and leave, and the downsizer who wants to stop maintaining a yard. The right neighborhood is different for each.
If this is you | Look at | Why |
|---|---|---|
First-time buyer working in the Sarasota area | Mainland Sarasota, Bradenton, Venice, North Port | Lowest entry points, and shorter commutes than the far south |
Buyer who wants walkability and culture | Downtown Sarasota 34236, Rosemary District | Walk to Main Street, the bayfront and the arts district |
Buyer who wants master-planned amenities | Lakewood Ranch 34202 and 34211, Waterside 34240, Wellen Park 34293 | Pools, fitness, trails and town centers, with CDD and HOA layered in |
Seasonal or lock-and-leave owner | Barrier island and near-coastal condos, Venice, Longboat Key | Association handles the exterior while you are away |
Buyer prioritizing value per square foot | North Port, Port Charlotte, Punta Gorda | Farthest from downtown Sarasota, and priced accordingly |
Downsizer who still wants a garage | Townhomes and paired villas across Sarasota and Manatee counties | Attached living without giving up private parking and storage |
Every one of these carries a different insurance profile and a different association structure. Two units in the same ZIP code can underwrite very differently based on building age, roof and construction type.
It can be, provided you buy into a well-run association with a funded reserve. The variable that determines the outcome is governance, not the view.
We will not publish appreciation forecasts. What we will say is structural. A building with a current milestone inspection, a funded reserve study, a fully insured master policy and clean minutes is straightforward for the next buyer to finance. A building with deferred maintenance and a thin reserve narrows your future buyer pool to cash, and that shows up in price.
That is why we treat association due diligence as the main event in a condo purchase, and the unit itself as secondary. You can renovate a kitchen. You cannot renovate a board.
Usually no, but sometimes yes, and the marketing name will not tell you. Most Southwest Florida townhomes are fee simple, meaning you own the home and the lot beneath it and belong to a homeowners association. Some attached homes marketed as townhomes are legally condominiums, meaning you own the interior and the association owns the structure. The distinction changes your insurance, your maintenance obligations, your association fee and how a lender underwrites the purchase. The recorded declaration settles it. We pull it before writing an offer.
Largely because of the structural inspection and reserve requirements Florida enacted after the Surfside collapse. Buildings three stories or higher must obtain milestone structural inspections and structural integrity reserve studies, and associations face limits on waiving reserves for the structural components those studies identify. Buildings that had been underfunding reserves for years had to start funding them, and some issued special assessments for repairs the inspection identified. A low fee in an older building is not necessarily a bargain. It may mean the work has not been funded yet.
Not automatically. Conventional lenders evaluate the project as well as the borrower, applying eligibility standards that consider reserves, deferred maintenance, insurance, litigation and the percentage of units owned by investors. A project that fails those standards may require a portfolio loan or a cash purchase. This matters twice: once when you buy, and again when you sell, because it determines who can finance your unit. Ask your lender to run the project early in the inspection period rather than discovering the issue at underwriting.
Many do. A Community Development District assessment is tied to the parcel and the district, not to the form of housing, so attached homes inside master-planned districts such as Lakewood Ranch, Waterside, Skye Ranch and Wellen Park frequently carry one. It appears on your annual county property tax bill rather than your association invoice, which is why buyers miss it. The amount is parcel-specific and changes when a district refinances. Beyond Realty pulls the current figure from the county tax roll for the exact address.
You generally need an HO-6 unit owner policy, which covers your interior, your belongings, your liability and, importantly, loss assessment coverage. The association carries a master policy on the structure and common elements. The two interact, and the seam between them is where owners get hurt. Read the master policy's wind deductible, because after a named storm that deductible is typically passed to owners as an assessment. Loss assessment coverage on your HO-6 is what absorbs it. Review both policies together, not separately.
Beyond Realty orders and reads the declaration, budget, reserve study, milestone inspection report, minutes and master insurance certificate for every condo and townhome purchase, inside the inspection period, while you can still walk. We also pull the CDD assessment from the county tax roll and get a live insurance quote on the specific unit.
Beyond Realty is based in downtown Sarasota and works across Sarasota, Manatee and Charlotte counties, including Lakewood Ranch, Waterside, Palmer Ranch, Venice, Nokomis, Osprey, Bradenton, North Port, Wellen Park, Port Charlotte and Punta Gorda. Get in touch or read more about Darren Dowling.
Darren Dowling, Broker-Owner Beyond Realty 2170 Main Street, Suite 103 Sarasota, FL 34237 (941) 204-0493
A practical fall home-selling strategy for homeowners in Sarasota, Lakewood Ranch, Manatee County, Sarasota County, and Charlotte County
We toured every Perry model at Seaire in Parrish. Here is who Perry Homes is, what is included, current move-in ready pricing from $499,900, and how Perry compares wit… Read more
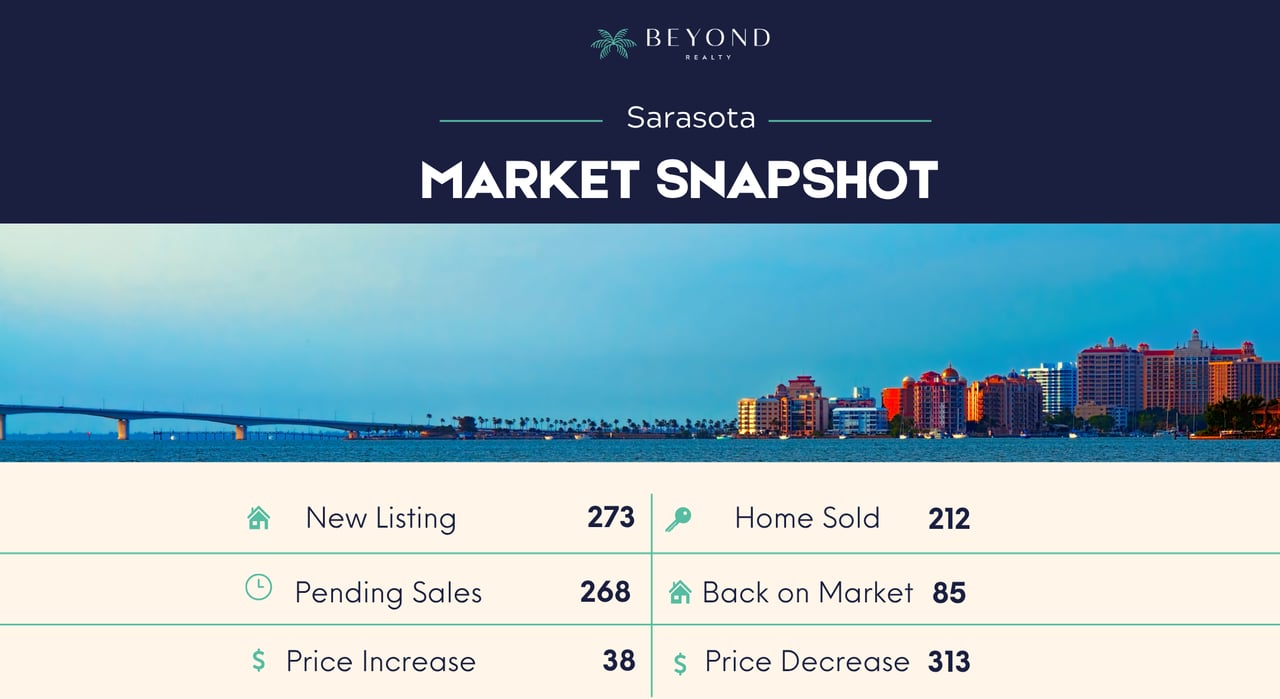

Ritz-Carlton, One Park, Bayso, The Edge, DeMarcay, The Collection, Epoch, Mira Mar and Saravela compared, with 2026 pricing, HOA costs and rental rules
Who it is for, how the rental program works for owners, how it compares with other downtown towers, and the questions buyers ask
You’ve got questions and we can’t wait to answer them.