Why Townhomes Are Popular With Today’s First-Time Buyers
Darren Dowling

Darren Dowling
Townhomes are the lowest priced attached product in Sarasota, Manatee and Charlotte counties, but the label hides two different legal forms. A fee simple townhome means you insure the building. A condominium form townhome is covered by the association master policy and needs project approval for FHA financing.
Key takeaways:
A townhome usually delivers more interior square footage per dollar than a condominium flat, with less exterior maintenance than a single family house. For a first purchase in Sarasota, Manatee or Charlotte county, that combination is hard to beat.
The second reason is the yard, or the lack of one. Most attached products in this market include exterior and landscape maintenance in the association dues, which removes both the time and the equipment cost from your budget. In a climate where lawns grow year round and roofs matter enormously, outsourcing that is not a small benefit.
The third reason is newer stock. A meaningful share of townhome inventory in this area was built recently, which means current building code, newer roofs and, often, better insurance pricing than a mainland house of the same price built decades earlier.
This is the question that decides your insurance bill, your loan options and your resale pool, and most buyers never ask it. The building can look identical either way.
Feature | Fee simple townhome | Condominium form townhome | Condominium flat | Single family house |
|---|---|---|---|---|
What you own | The structure and the land under it | The airspace inside the unit | The airspace inside the unit | Everything |
Who insures the building | You, with a standard homeowner policy | The association master policy | The association master policy | You |
What you carry | Homeowner policy on the structure | HO-6 interior and contents policy | HO-6 interior and contents policy | Homeowner policy |
Roof responsibility | Usually yours, sometimes the association's, read the documents | The association | The association | Yours |
FHA financing | No project approval needed | Requires an approved condo project | Requires an approved condo project | No project approval needed |
Monthly dues | HOA, typically lower | Association, typically higher because it includes building insurance | Association | None or voluntary |
Who the resale pool is | Anyone who can buy a house | Buyers whose lender accepts the project | Buyers whose lender accepts the project | Anyone |
Two practical consequences. First, a lower monthly due is not automatically cheaper: a fee simple townhome with 200 dollars of dues plus your own building insurance can cost more per month than a condominium form townhome with higher dues that include the master policy. Compare the total, not the dues line. Second, condominium form product is only as financeable as its project approval and its reserves, which is why the reserve study matters more here than almost anywhere else.
New townhome construction clusters in the master planned communities, while the value resale product sits on the mainland. The two serve very different buyers.
Where | Area and ZIP | What it is | Note |
|---|---|---|---|
Emerald Landing at Waterside | Lakewood Ranch 34240 | Newer townhomes by David Weekley Homes | Sarasota County Schools, CDD assessment on the tax bill |
Bungalow Walk at Waterside | Lakewood Ranch 34240 | Dream Finders Homes | Walkable to Waterside Place |
Ashcombe at Wellen Park | North Port 34293, Venice mailing address | D.R. Horton townhomes | Entry price point in Wellen Park |
Palmera at Wellen Park | North Port 34293 | Mixed single family, townhomes and condos | Widest price range in one village |
Mainland Sarasota | 34231, 34232, 34233 | Established attached product | Often no CDD, older roofs, verify insurance |
Venice and North Port | 34285, 34292, 34293, 34287 | A mix of newer and established | Generally the lowest price per square foot in the region |
Bradenton and Manatee County | 34203, 34205, 34207 | Established and newer communities | Manatee County Schools |
Community lineups change as phases sell out. Treat this as where to look rather than what is available this week.
The documents, not the finishes. A townhome with a beautiful kitchen and an underfunded association is a worse purchase than a plain one with healthy reserves.
What to request | Why it matters |
|---|---|
The declaration and governing documents | Tells you whether it is fee simple or condominium form, and who owns the roof |
The association budget | Shows what dues actually cover, and whether building insurance is included |
The reserve study and reserve funding status | Underfunded reserves become special assessments, and Florida's structural integrity reserve rules have changed how associations must budget |
Assessment history and any pending special assessment | A pending assessment is a price negotiation, if you know about it in time |
Rental restrictions and minimum lease terms | Decides whether you could ever rent it out, and affects resale demand |
The master policy declarations page | Tells your insurance agent what your HO-6 actually needs to cover |
The CDD assessment for the lot, if applicable | Billed on the annual county tax bill, not by the association |
Roof age and the wind mitigation report | Drives your premium whether you insure the building or not |
The Florida specific item in that list is the reserve study. Reserve requirements and inspection obligations have tightened for many association governed buildings in the state, and associations have funded that through dues increases or assessments. A buyer who reads the reserve study avoids inheriting a number someone else already knew about.
Buyers who want a boat, an RV, a workshop, a fenced yard for large dogs, or a short term rental income stream should look hard at the restrictions before they fall in love. Attached product trades autonomy for maintenance relief, and the trade is in the documents.
Also consider resale liquidity. A fee simple townhome sells to anyone who can buy a house. A condominium form townhome sells only to buyers whose lender will finance that project, which narrows the pool if the association's approval status or reserve funding is weak. If you expect to move within a few years, that difference matters more than the monthly dues.
If you want the declaration, the reserve study and the insurance picture read on a specific townhome before you write an offer, contact Beyond Realty. You can also read more about Darren Dowling, Broker-Owner.
Sometimes, and the deed is the only reliable answer. Townhome describes a building style: attached units, usually two stories, each with its own entrance. The legal form can be fee simple, where you own the structure and the land beneath it, or condominium, where you own the airspace inside the unit and the association owns the building. That distinction decides who insures the roof, whether you carry a homeowner policy or an HO-6, and whether FHA financing requires project approval. Read the declaration before you assume.
Usually lower on the dues line, but that is not the same as cheaper. A condominium association's dues typically include the master insurance policy on the building, which in Florida is a large number. A fee simple townhome's HOA dues usually cover landscaping and common areas only, and you buy your own building insurance separately. Compare the total of dues plus your own insurance across both, because a lower dues figure with a separate premium can easily cost more each month.
That depends on two independent sets of rules, and both have to allow it. Local zoning sets the minimum rental term for the parcel, and the association documents set their own limits on lease length, how many leases per year are permitted, and sometimes a waiting period after purchase before you may rent at all. Association rules are frequently stricter than zoning. Get both in writing during your inspection period if rental income is part of your plan.
Generally yes. Townhomes in Waterside at Lakewood Ranch, in Wellen Park and in most newer master planned communities sit inside a community development district or a comparable special district, and the resulting infrastructure assessment appears on your annual county property tax bill, separate from your association dues. The amount varies by village, by phase and by lot, and so does the remaining bond term. Ask for the current annual figure for your specific lot rather than a community average.
It depends far more on the association than on the product type. A well run association with funded reserves, a clean assessment history and no financing obstacles keeps a townhome liquid and competitive. An association with deferred maintenance, a special assessment history or a lapsed condo project approval shrinks the pool of buyers who can finance it, which shows up directly in price. That is why the reserve study and the assessment history are the first documents Beyond Realty requests on any attached product.
Darren Dowling, Broker-Owner, Beyond Realty, 2170 Main Street, Suite 103, Sarasota, FL 34237, (941) 204-0493.
How VA Home Loan Benefits, More Negotiating Opportunities, and Local Real Estate Market Conditions Could Help Veterans and Active-Duty Service Members Buy a Home in Sa… Read more
What Buyers and Sellers Need to Know About Mortgage Rates, Home Values, and Real Estate Market Trends in Sarasota, Lakewood Ranch, Manatee County, and Charlotte County.
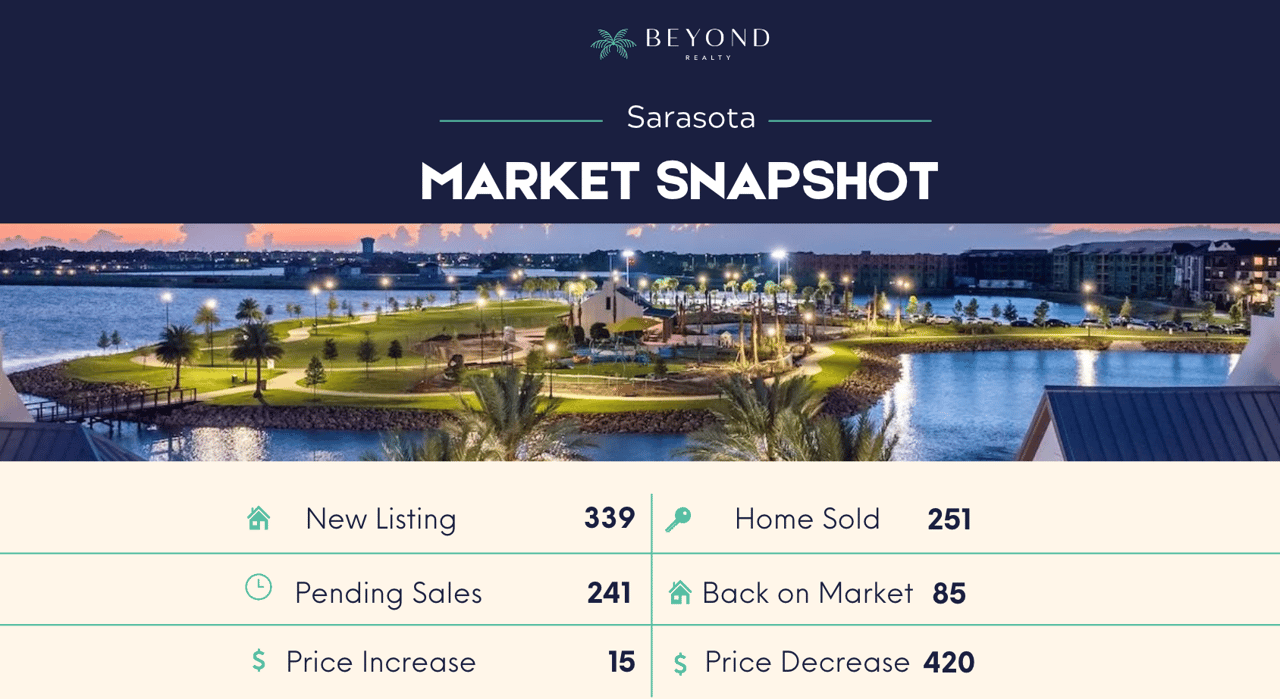
Closed Sales and Pending Activity Rise in Sarasota County as Pricing Adjustments Continue Across Both Markets
You’ve got questions and we can’t wait to answer them.