Moving to Sarasota in 2026: Is It Still Worth It for High-Tax State Buyers?
Darren Dowling

Darren Dowling
Moving from a high tax state to Sarasota still pencils out in 2026 for most households, but the savings are smaller than the headline. Florida levies no state individual income tax and no estate tax. Offsetting that are property insurance, CDD assessments and a reset assessed value after purchase.
Key takeaways:
For most households with meaningful earned, retirement or investment income, yes, but the margin is narrower than it was a few years ago. The income tax savings did not shrink. The Florida cost of ownership rose.
The honest framing is this. Your savings equal whatever your former state would have taxed on your particular income mix. That number is highly personal: a retiree with Social Security and modest withdrawals from a state that already exempts retirement income saves far less than a high earner leaving a state with a top marginal rate near double digits. Against that, you take on Florida property insurance, which has been the most volatile line item in the state, plus any district assessment attached to the parcel.
What makes the move work or fail is rarely the income tax question. It is whether you choose a property whose insurance and assessment profile does not eat the savings.
Three things change: your state income tax goes to zero, your state estate tax exposure goes to zero, and your property tax basis resets to the price you paid. The third one surprises people most.
Item | High tax state | Florida and Sarasota or Manatee County |
|---|---|---|
State individual income tax | Applies to wages, retirement income and investment income depending on the state | None |
State estate or inheritance tax | Several states impose one | None at the state level |
Property tax assessment | Varies by state mechanics | Resets to market on sale, then capped at 3 percent or CPI, whichever is lower, once you homestead |
Homestead relief | Varies widely | Up to 50,000 dollars of exemption, with the second 25,000 not applying to school district levies |
Transfer cost on purchase | Varies | Florida documentary stamp tax on the deed, 70 cents per 100 dollars of consideration outside Miami-Dade |
Property insurance | Usually a smaller line | Often the largest single variable cost, driven by wind, roof age and flood |
District assessments | Uncommon in many states | Common in master planned communities, billed on the annual tax bill |
The assessment reset is the one that quietly damages budgets. When you look at a listing and see a modest annual tax figure, that figure often belongs to a seller who homesteaded the property years ago and has been protected by Florida's Save Our Homes cap, which limits annual assessed value increases to 3 percent or the change in the consumer price index, whichever is lower. On sale, that protection ends and the property is reassessed. Your bill can be substantially higher than the one printed in the listing, for the identical house.
Insurance, district assessments and HOA dues are the three offsets, and only one of them is visible on a listing. Budget all three before you decide the move works.
Offsetting cost | What drives it | How to get a real number |
|---|---|---|
Windstorm and hazard insurance | Roof age and material, construction type, distance to coast, opening protection | A bound quote on the specific address, not a community estimate |
Flood insurance | FEMA zone, elevation, foundation, distance to water under Risk Rating 2.0 | The flood determination for the parcel, plus a quote |
CDD or special district assessment | The infrastructure bond on that village and phase | The current annual amount and the remaining bond term for that lot |
HOA or condo association dues | Amenities, reserves, building age, insurance at the association level | The budget, the reserve study and the last two years of minutes |
Property taxes after reset | Your purchase price, the county millage, your homestead status | The county property appraiser's parcel record and your own math |
Condominium buyers need one extra step. Florida's structural integrity reserve requirements have changed how older associations budget, and some buildings have funded that through assessments or dues increases. Ask for the reserve study and the association's assessment history before you fall in love with a view.
Buying a house in Sarasota does not make you a Florida resident for tax purposes. Changing your domicile does, and high tax states audit the difference. Domicile is about where your life is centered, and the evidence is cumulative.
Step | Why it matters |
|---|---|
File a Declaration of Domicile with the Clerk of the Circuit Court | A formal, dated statement of intent under Florida law |
Apply for the Florida homestead exemption with the county property appraiser | Also the mechanism for Save Our Homes and portability, with a March 1 filing deadline |
Get a Florida driver license and register your vehicles | Among the first items an auditor checks |
Register to vote in your Florida county and actually vote | Weighs heavily in residency determinations |
Move your primary banking, advisors, doctors and dentists | Shows the center of your life, not just a mailing address |
Update estate documents to Florida law | Also protects the no state estate tax benefit |
Track your days | Several states apply a day count test alongside domicile, so keep contemporaneous records |
The most common failure is the half move: a Sarasota address, a Florida license, and a former state house that the family still uses most of the year. If you keep a home in your old state, keep records, count days and expect scrutiny. This is a conversation for a CPA or tax attorney licensed in both states. Beyond Realty is not a tax advisor, and we tell clients that plainly rather than guessing at their returns.
The right ZIP depends on which offset you are least willing to pay. If insurance is your concern, go inland. If you want the walk, pay for downtown. If you want new construction and schools, you will accept a district assessment.
Priority | Where to look | ZIP | The tradeoff |
|---|---|---|---|
Lowest insurance exposure | Inland Sarasota, Lakewood Ranch, Palmer Ranch | 34232, 34233, 34202, 34211, 34238 | Further from the Gulf, more driving |
No or low district assessment | Established mainland neighborhoods, Gulf Gate, South Gate, Sarasota Springs | 34231, 34239, 34233 | Older homes, roof age matters for insurance |
Walkable, low maintenance | Downtown Sarasota, Rosemary District, Golden Gate Point | 34236 | Condo association dues and reserve obligations |
New construction with schools | Lakewood Ranch, Waterside, Wellen Park | 34202, 34211, 34240, 34293 | CDD or special district assessment on the tax bill |
Coastal and water access | Siesta Key, Lido Key, Bird Key, Casey Key, Nokomis | 34242, 34236, 34275 | Highest insurance and flood exposure, bridge dependency |
Value per square foot | Venice, North Port, Bradenton | 34293, 34287, 34203 | Longer drives to Sarasota arts, dining and the main hospital |
The case against is simple: if your income is mostly already untaxed by your current state, and you buy a coastal property with a high insurance profile, you can move and save nothing. It is worth modeling before you list your house.
Three other honest points. Hurricane exposure is real and it is a cost as well as a risk, and the insurance market reflects that. Seasonal density from roughly November through April changes traffic, restaurant waits and bridge times in a way that visitors on a February house hunting trip do not always register as permanent. And if your family and your professional network are in the state you are leaving, the non financial cost of the move is the part no spreadsheet captures.
If you want the real numbers for your situation, including a bound insurance quote, the district assessment and a reset tax estimate on a specific parcel, contact Beyond Realty. You can also read more about Darren Dowling, Broker-Owner, who works with relocating buyers across Sarasota and Manatee counties.
No. Buying property changes your real estate holdings, not your domicile. Domicile is where your permanent home and the center of your life are, and high tax states audit claimed moves carefully. The practical steps are to file a Declaration of Domicile with the Clerk of the Circuit Court, file for the Florida homestead exemption with the county property appraiser, obtain a Florida driver license, register your vehicles, register to vote, and move your banking, advisors and medical care. Talk to a CPA or tax attorney licensed in both states before you rely on any of this.
More than the figure in the listing, in most cases. Florida's Save Our Homes provision caps annual assessed value increases at 3 percent or the change in the consumer price index, whichever is lower, for homesteaded owners, so a long time owner's assessed value can sit far below market. When the home sells, that protection ends and the property is reassessed. Your own homestead exemption, worth up to 50,000 dollars of assessed value, then applies going forward, and portability can carry up to 500,000 dollars of accumulated benefit from a prior Florida homestead.
It can, and whether it does is mostly a function of which property you buy rather than the market in general. The drivers are roof age and material, construction type, opening protection, distance to the coast, and the FEMA flood zone and elevation of the parcel. Two homes at the same price, one inland in Zone X with a new roof and one on a barrier island with an older roof, can quote very differently. Never budget from an average. Get a bound quote on the specific address during your inspection period.
A community development district is a special taxing district that financed the roads, drainage and amenities in a master planned community. The resulting assessment appears on your annual county property tax bill, separate from your HOA dues, and it runs until the bond is repaid. If you buy in Lakewood Ranch, Waterside, Wellen Park or most newer master planned communities in the area, you will almost certainly have one. Older mainland Sarasota neighborhoods generally do not. Ask for the current annual amount and the remaining term for the specific lot.
For many relocating buyers, yes. A season of renting lets you experience the summer heat and the winter density, test commutes, and learn which neighborhoods actually suit you before you commit. It also lets you establish Florida domicile steps early. The counterargument is cost: seasonal rentals from January through March are priced for the season, and a year of renting is money you do not build equity with. The right answer depends on how certain you are about the area, not about the state.
Darren Dowling, Broker-Owner, Beyond Realty, 2170 Main Street, Suite 103, Sarasota, FL 34237, (941) 204-0493.
How VA Home Loan Benefits, More Negotiating Opportunities, and Local Real Estate Market Conditions Could Help Veterans and Active-Duty Service Members Buy a Home in Sa… Read more
What Buyers and Sellers Need to Know About Mortgage Rates, Home Values, and Real Estate Market Trends in Sarasota, Lakewood Ranch, Manatee County, and Charlotte County.
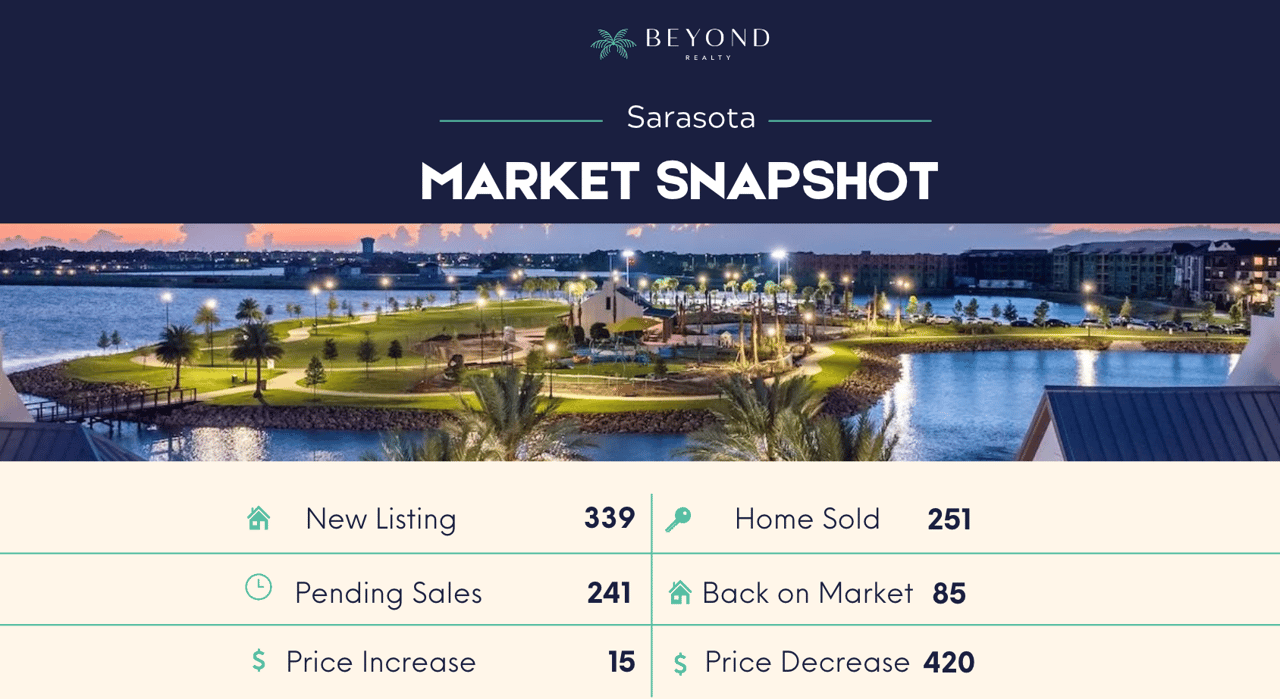
Closed Sales and Pending Activity Rise in Sarasota County as Pricing Adjustments Continue Across Both Markets
You’ve got questions and we can’t wait to answer them.